A pre-minutes market check with participation still uneven
November 18, 2026, pre-release edition. The fund figures below are sampled market-data snapshots with latest trade stamps from 12:36:00–12:36:29 CST and 12:46:29–12:47:01 CST. They are historical fund prints, not 13:00 quotes or cash index closes. The Federal Reserve scheduled the October FOMC minutes for 13:00 CST. This edition does not report their contents or the market reaction.
MARKET | GREEN IN POCKETS, FLAT AT THE CENTER
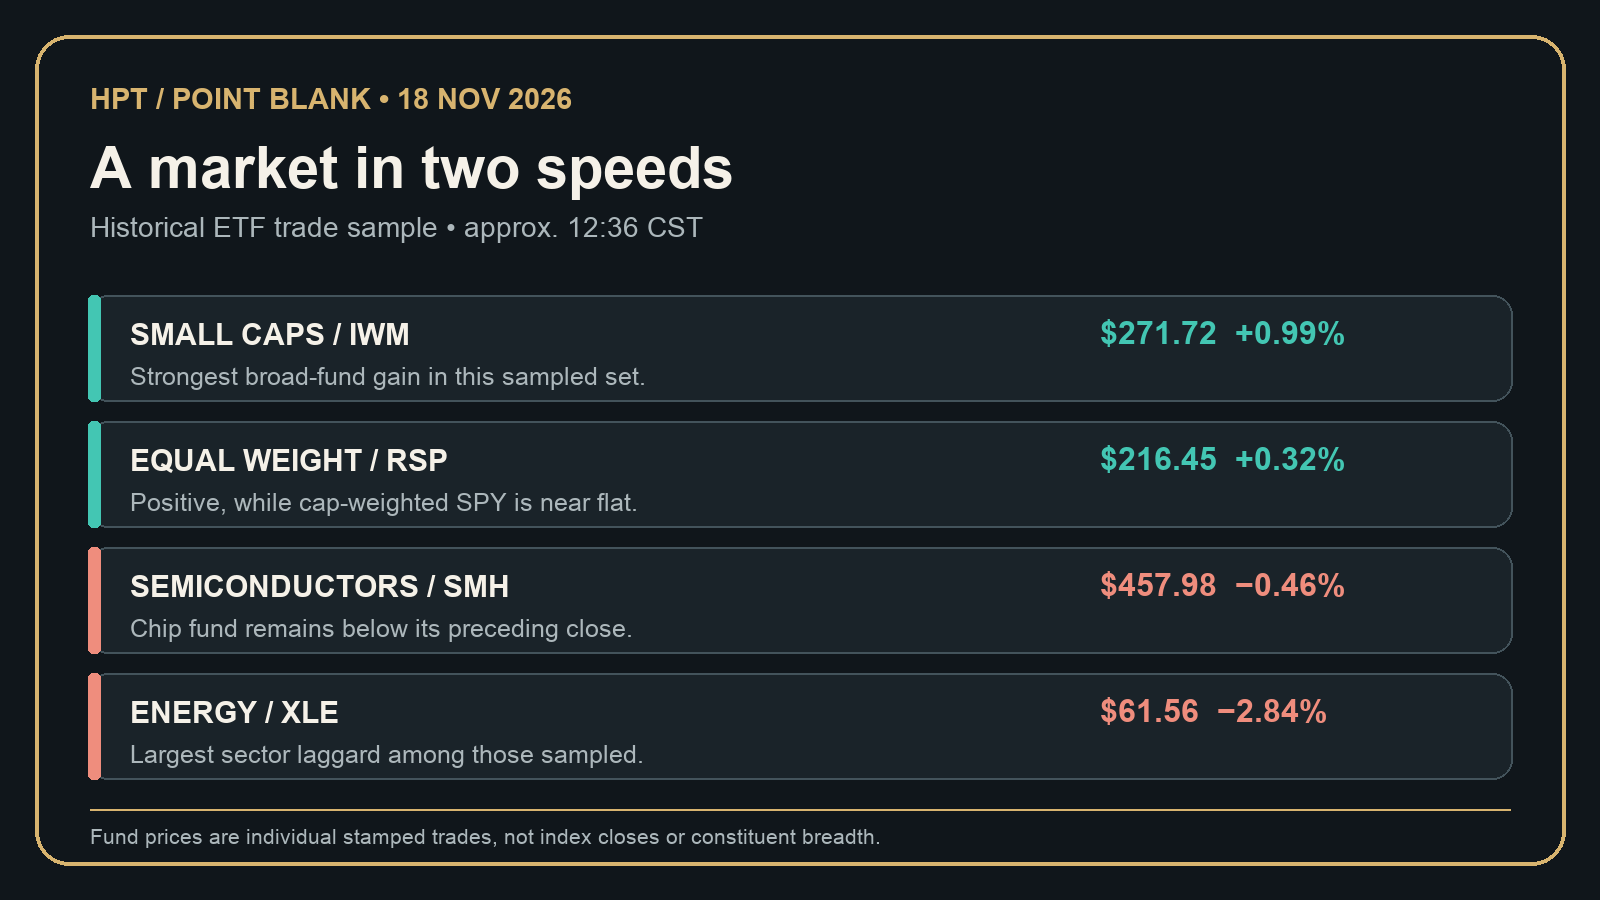
At 12:36, SPY was $732.38 (−0.01%), QQQ $660.15 (+0.49%), IWM $271.72 (+0.99%), DIA $503.47 (−0.76%) and RSP $216.45 (+0.32%) versus their preceding closes. The small-cap fund retained the strongest gain among these five proxies. Equal-weight RSP and QQQ were positive while SPY hovered near flat and DIA remained negative. That split supports a selective-repair description; it does not prove most S&P constituents rose or that the market completed a breakout.
Compared with the 12:03 sampled board in the previous edition, all five fund prices improved. A separate pre-release check around 12:46–12:47 showed SPY $733.61 (+0.16%), QQQ $661.93 (+0.76%), IWM $271.96 (+1.08%), DIA $503.85 (−0.68%) and RSP $216.58 (+0.38%). SPY had moved above its preceding close, while DIA remained negative. These are separate timestamps, not continuous tape or a verified held retest.
SECTORS | TECHNOLOGY RECOVERS; CHIPS DO NOT CONFIRM
At 12:36, XLK was $163.60 (+0.21%), SMH $457.98 (−0.46%), XLF $56.65 (−0.74%) and XLE $61.56 (−2.84%). Technology’s return above its prior close was constructive for the QQQ-led side, but semiconductors remained negative. Financials and energy also lagged. Nvidia’s November 17 fiscal-third-quarter report showed $115.8 billion in revenue and $107.6 billion in Data Center revenue, evidence of company-level AI infrastructure demand. It does not imply every chip constituent or the SMH fund must rise today. The divergence argues for fresh participation before treating QQQ strength as broad confirmation.
MACRO | THE CLOCK IS KNOWN; THE MINUTES ARE NOT
The U.S. Census Bureau and HUD released October New Residential Construction at 07:30 CST. Building permits were 1.295 million at a seasonally adjusted annual rate, 7.4% below revised September. Housing starts were 1.309 million; the reported 9.9% monthly rise carried a ±16.8 percentage-point margin of error under the agency’s 90% standard. That starts change is not statistically distinguishable from zero. Permits and starts measure different stages of the pipeline. The report does not establish the cause of this midday market split.
The Federal Reserve calendar set the October meeting minutes for 13:00 CST. At the price source cutoff they were unreleased. A later edition must review the released text and a newly stamped market sample before making a post-release claim. A pre-event thesis must account for gaps, spreads and rapid repricing.
CROSS ASSET | DIFFERENT INSTRUMENTS, DIFFERENT CLOCKS
At 12:36, GLD, a gold fund rather than spot metal, was $342.78 (−2.75%). USO, an oil fund rather than crude futures, was $135.81 (−3.16%). The latest completed U.S. Treasury daily par curve checked for this desk was dated November 17, with the 10-year at 5.10%; that is historical daily data, not a live midday yield. These differently timed figures alone prove no causal link to equity funds.
DECISION ROUTE | CONDITIONAL, WITH RISK DEFINED
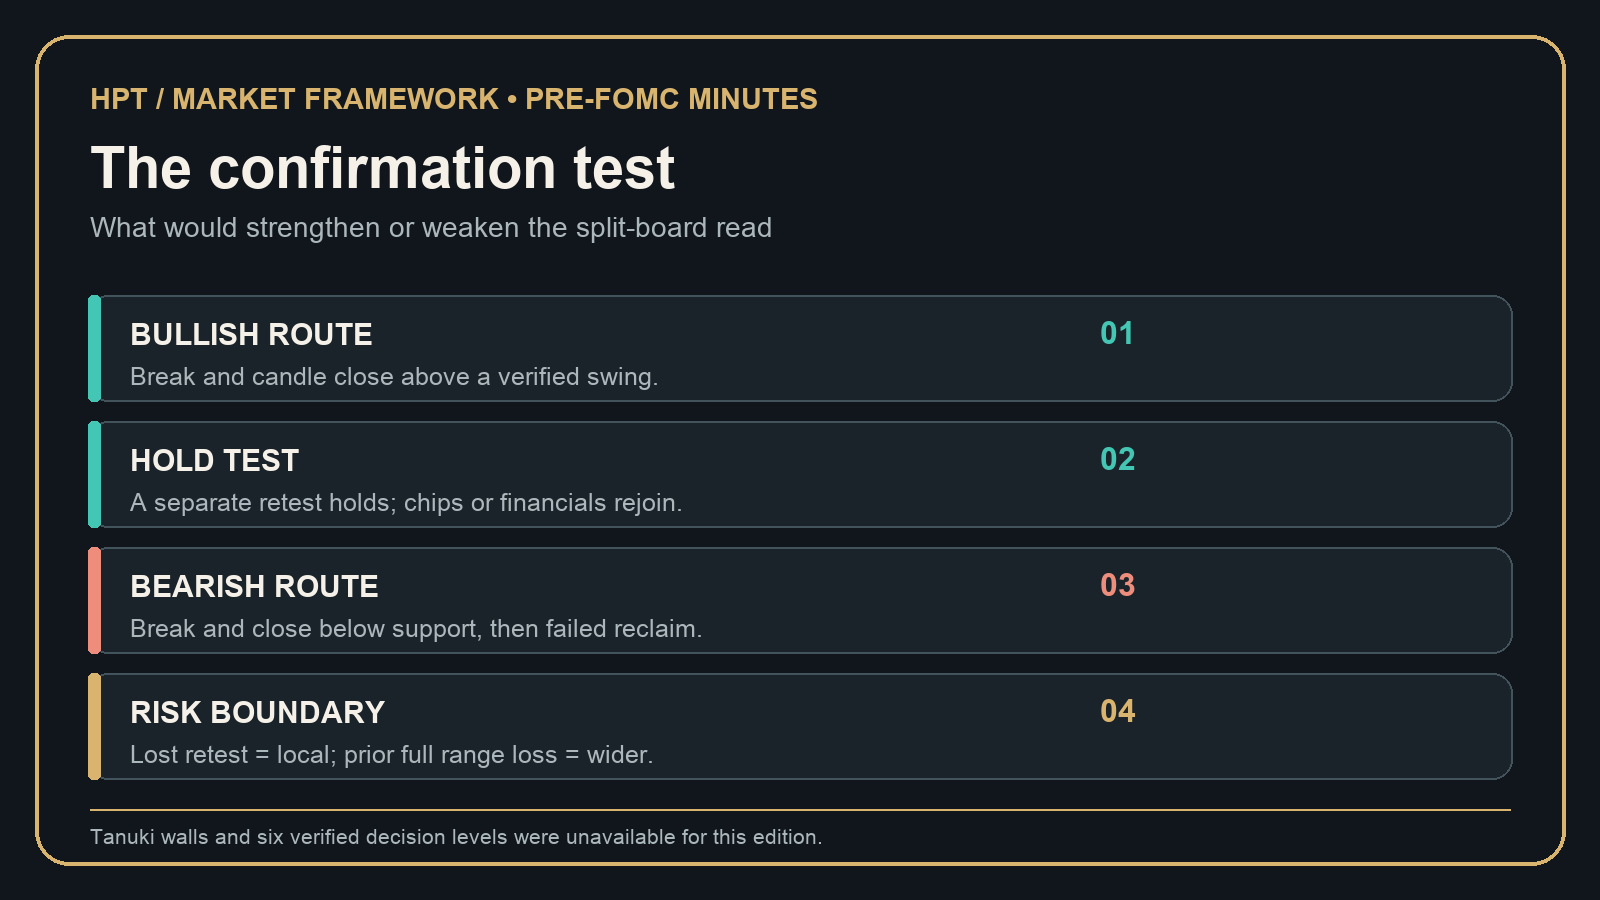
My near-term lean is selectively constructive but not yet broad-market bullish. QQQ, IWM and RSP above their prior closes show some support; SMH, XLF, XLE and DIA below theirs show the repair’s limit. A bullish route needs a break and candle close above a verified local swing, followed by a separate held retest, with equal-weight and a lagging chip or financial proxy improving. Failure of that retest is local invalidation; sustained loss of the preceding full cash-session range is wider invalidation. A bearish route needs a break and close below observed support followed by a failed reclaim, not one volatile event candle. These sampled ETF marks establish neither sequence.
The six-level technical map remains incomplete. Authenticated Tanuki put- and call-wall definitions and expiry scope, plus two verified upside and two downside checkpoints, were not established for this edition. I am not labeling a fund price, Fibonacci line or delayed preview as an options wall, nor claiming a gamma flip, position, fill or trade result. The boards are explanatory market-data and process visuals, not native TradingView captures.
After the minutes, which matters more: semiconductors and financials rejoining QQQ, or RSP and IWM losing relative strength?
Sources and timing: fund snapshots stamped 12:36:00–12:36:29 and 12:46:29–12:47:01 CST November 18; prior desk sample around 12:03 CST; Census/HUD October New Residential Construction released November 18 at 07:30 CST; Nvidia fiscal-third-quarter investor release November 17; U.S. Treasury Daily Par Yield Curve Rates November 17; Federal Reserve calendar, October FOMC minutes scheduled 13:00 CST.