# Point Blank: Nasdaq Strength Still Needs Wider Confirmation
*November 18, 2026 pre-open update. TradingView continuous-futures snapshot at about 07:11 CST, before the scheduled 07:30 CST October housing release. Futures prices and daily comparisons can move; these are not cash-index returns.*
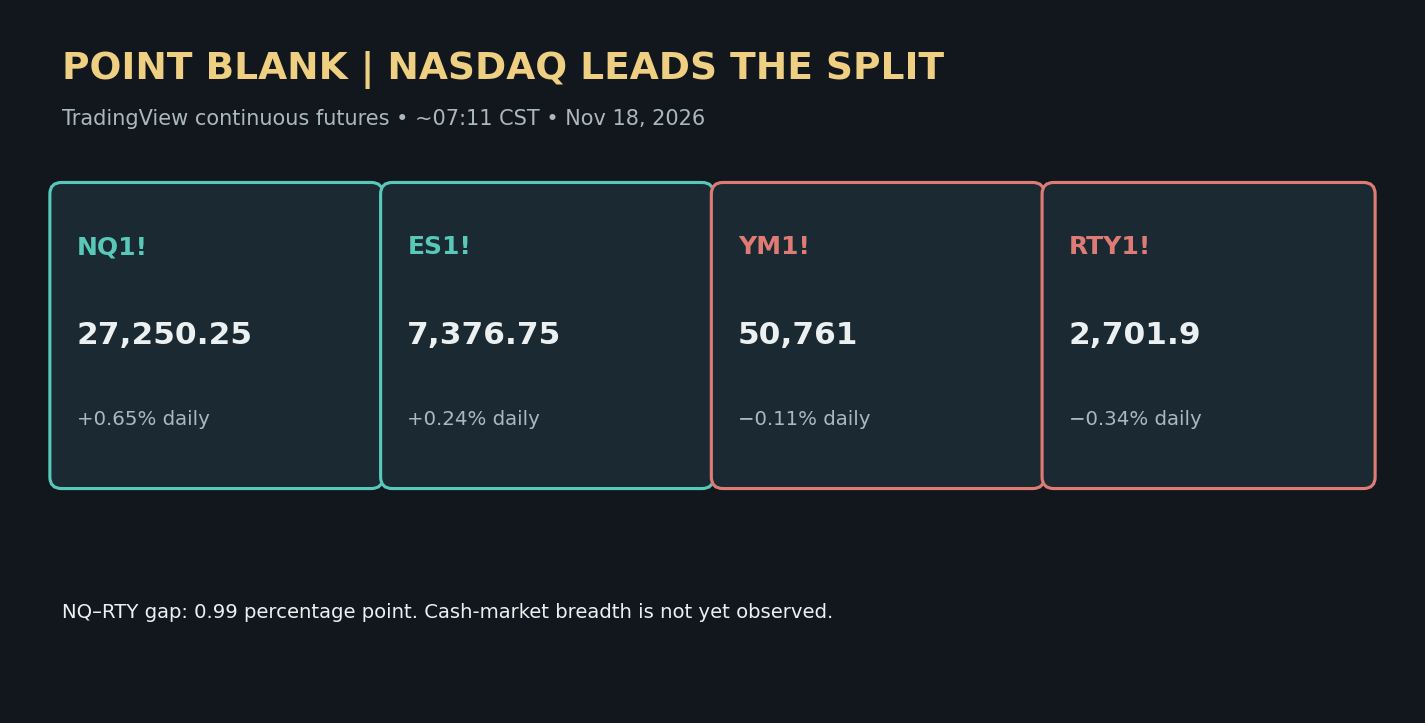
The market’s first decision is whether a Nasdaq-led rebound can spread. At the 07:11 check, NQ1! was 27,250.25 (+0.65% on TradingView’s displayed daily comparison) and ES1! was 7,376.75 (+0.24%). YM1! was 50,761 (−0.11%) and RTY1! 2,701.9 (−0.34%). That leaves a 0.99 percentage-point NQ–RTY gap. Nasdaq strength improved from our earlier 06:38 snapshot (+0.60%), while small-cap futures stayed negative. The direction is constructive for big tech, but this is still a split futures board, not proof of a broad cash-market recovery.
## Macro clock
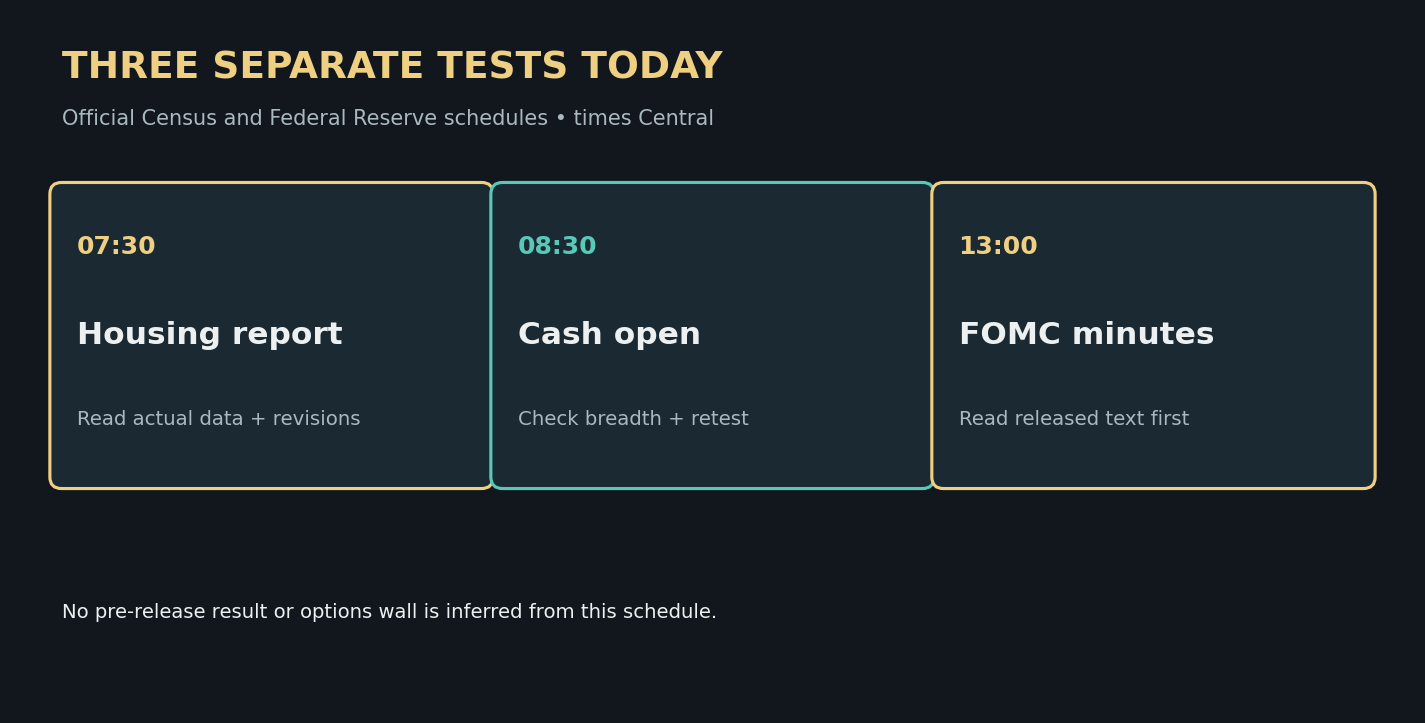
Census schedules October New Residential Construction for 8:30 a.m. Eastern / 7:30 a.m. Central. The actual permits, starts and completions were not yet available at this cutoff. Read the three series separately, the single-family/multi-family mix and prior-month revisions. A housing surprise can change the rates and homebuilder narrative, but it cannot by itself verify the day’s equity direction. The cash open comes at 8:30 Central, when participation can finally be checked. Federal Reserve October 27–28 FOMC minutes are scheduled for 1:00 p.m. Central and remain a later, unreleased catalyst at this cutoff.
## Cross-assets and fundamental lens
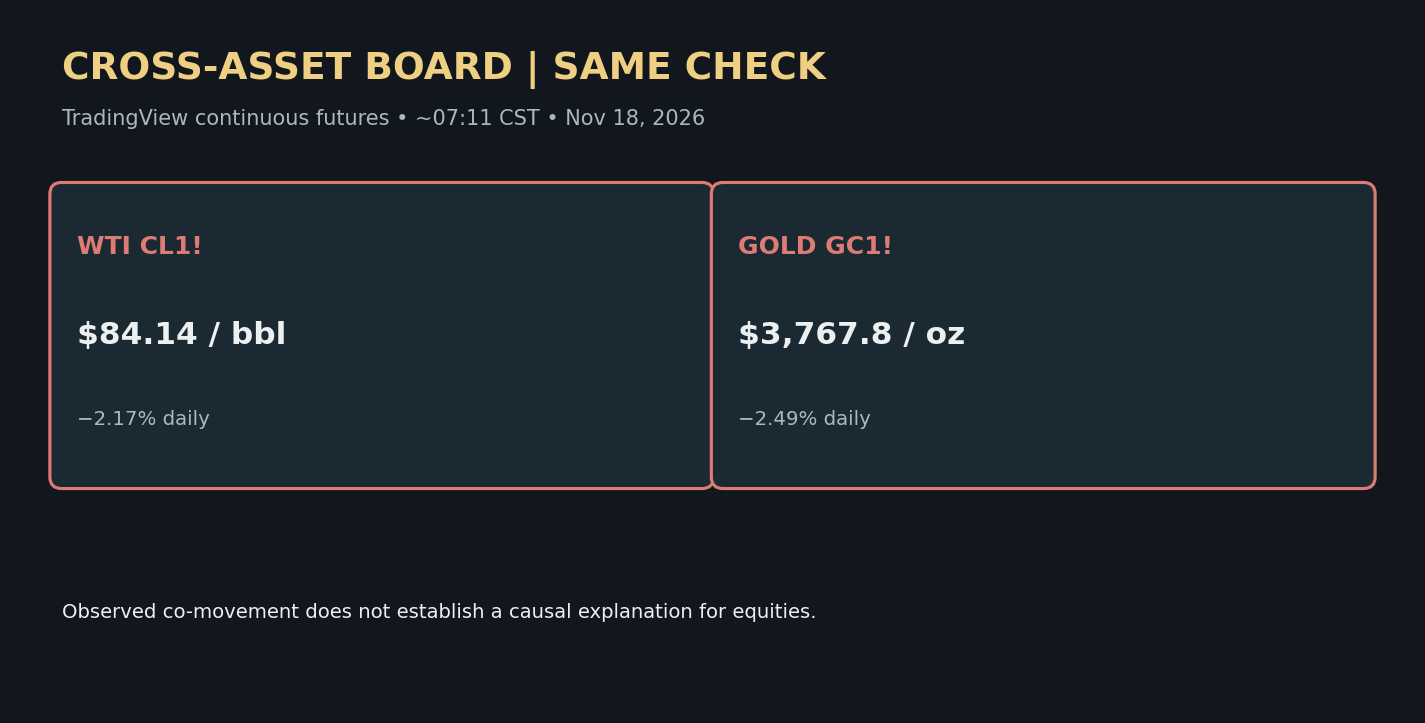
At the same 07:11 TradingView check, continuous WTI CL1! was $84.14/bbl (−2.17%) and gold GC1! $3,767.8/oz (−2.49%) on their displayed daily comparisons. Neither move supplies a proven cause for the equity split. Nvidia’s November 17 company release reported fiscal-third-quarter revenue of $115.8 billion and Data Center revenue of $107.6 billion; that keeps AI spending central to the fundamental discussion. It does not prove smaller companies or cyclical groups are participating. Tuesday’s completed cash session remains historical context: S&P 500 7,340.53 (−1.03%), Russell 2000 2,701.87 (−1.50%), VIX 25.46 (+11.13%), and all eleven S&P sectors lower. Today’s pre-open quotes have not rewritten those cash results.
## Decision framework
My lean is cautiously bullish for the Nasdaq-led rebound and neutral on the whole market until breadth improves. For a bullish route, wait for a selected instrument to break and close above an observed opening swing, then hold a distinct retest; confirmation is stronger if Russell, Dow and cash breadth join. Losing the retest is local invalidation; a sustained fall back through the prior completed cash range is wider invalidation. For a bearish route, require a break and close below an observed pullback swing and a separate failed reclaim. A red Russell quote by itself is insufficient. The upcoming housing print and 8:30 cash open may change these conditions, so the chart and levels must be refreshed before any execution claim.
The six-level technical decision map remains **unverified**: no authenticated Tanuki put-wall and call-wall definitions, matching expiry scope or two upside/two downside checkpoints were validated for this edition. The visuals below show the source-labeled futures snapshot and event/confirmation sequence. They are explanatory panels, not a native TradingView technical chart or an options-wall substitute.
Which happens first after housing and the cash open: broader participation, or another Nasdaq-only advance?
*Sources: TradingView NQ1!, ES1!, YM1!, RTY1!, CL1!, GC1! at ~07:11 CST November 18; U.S. Census New Residential Construction release schedule; Federal Reserve November 2026 calendar; Nvidia November 17 investor release. Prior cash close figures are historical November 17 data. No position or trade result is asserted.*