November 18, 2026 late-morning cash-session check. Delayed ETF latest trades below were stamped 10:51:23–10:52:05 CST and reviewed around 11:10 CST, against November 17 closes. This is a historical, asynchronously timed fund sample, not live 11:10 quotes, cash-index closes or a constituent advance/decline count. Fed October meeting minutes remained scheduled for 13:00 CST and were unreleased at this cutoff.
MARKET | THE SMALL-CAP EXCEPTION IS STILL NARROW
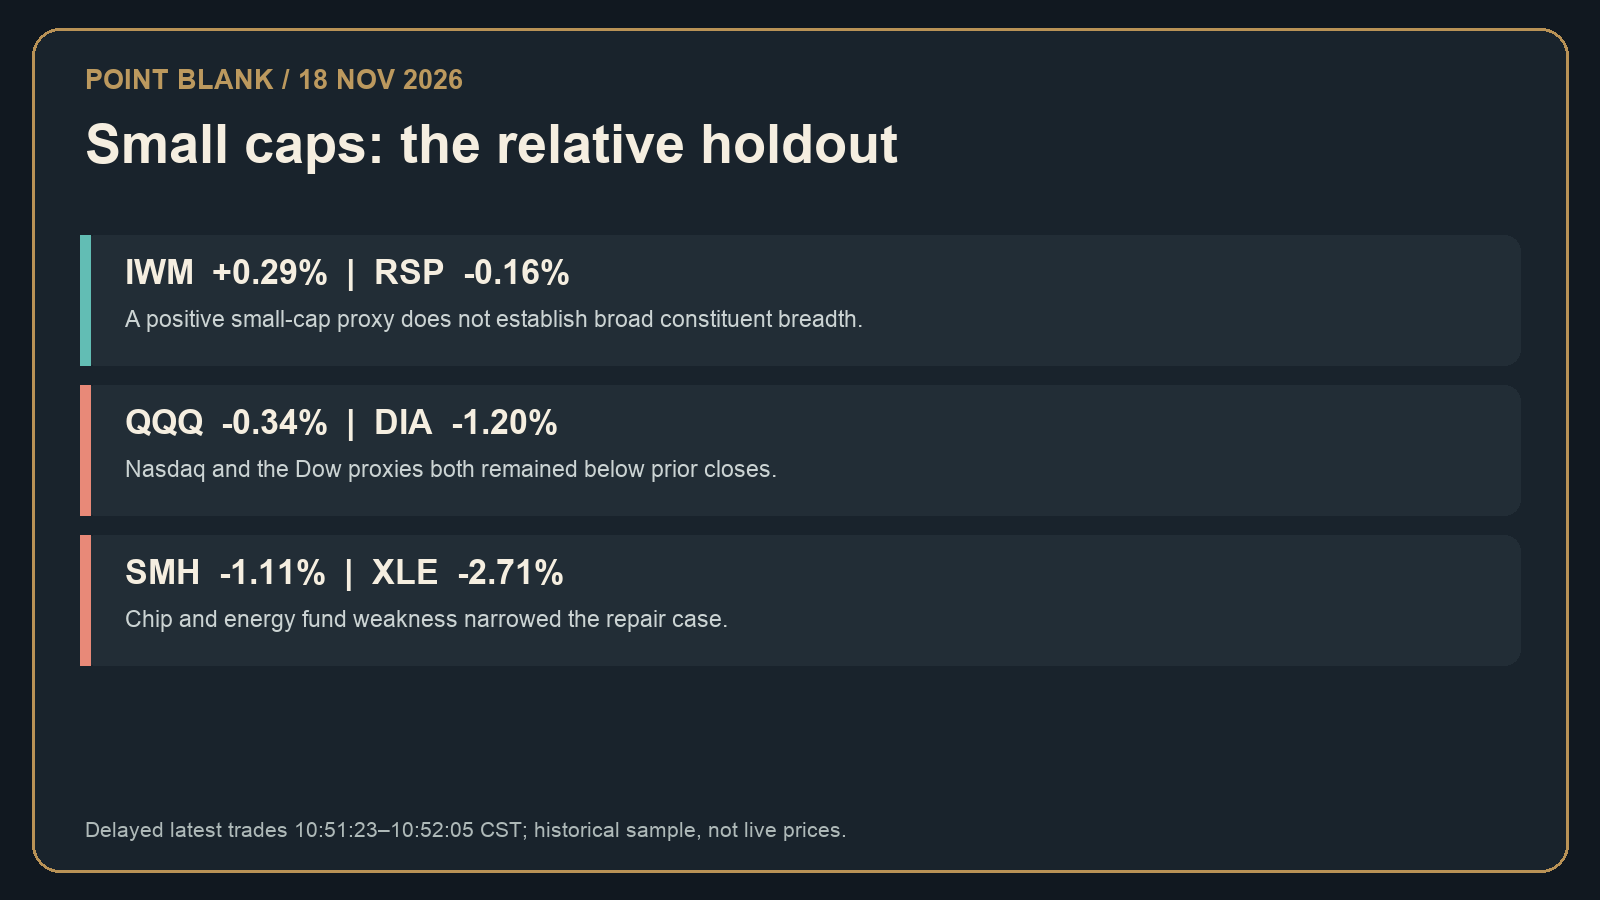
IWM was $269.84 (+0.29%) while SPY was $728.14 (−0.59%), QQQ $654.69 (−0.34%), DIA $501.21 (−1.20%) and equal-weight RSP $215.41 (−0.16%). IWM held above its prior close, but the other broad proxies did not. Equal weight remained negative and the Dow lagged most. A positive IWM print does not prove that the market’s constituents are broadly advancing. It shows relative fund performance at these timestamps. QQQ has crossed its prior close in both directions during earlier sampled windows, so a single positive tick would not establish a stable Nasdaq repair.
SECTORS | CHIPS LOSE MORE GROUND
SMH was $455.00 (−1.11%), XLK $162.25 (−0.62%), XLF $56.54 (−0.93%) and XLE $61.64 (−2.71%). The semiconductor and technology fund prints were weaker than the 10:25 sample in the preceding edition; energy remained the weakest of these sector proxies. These ETF changes do not establish the reason for each constituent’s move. A broader bullish claim needs a later synchronized sample with RSP, financials and semiconductors participating rather than relying on IWM alone.
MACRO | HOUSING DOES NOT PROVIDE A CLEAN COUNTERSIGNAL
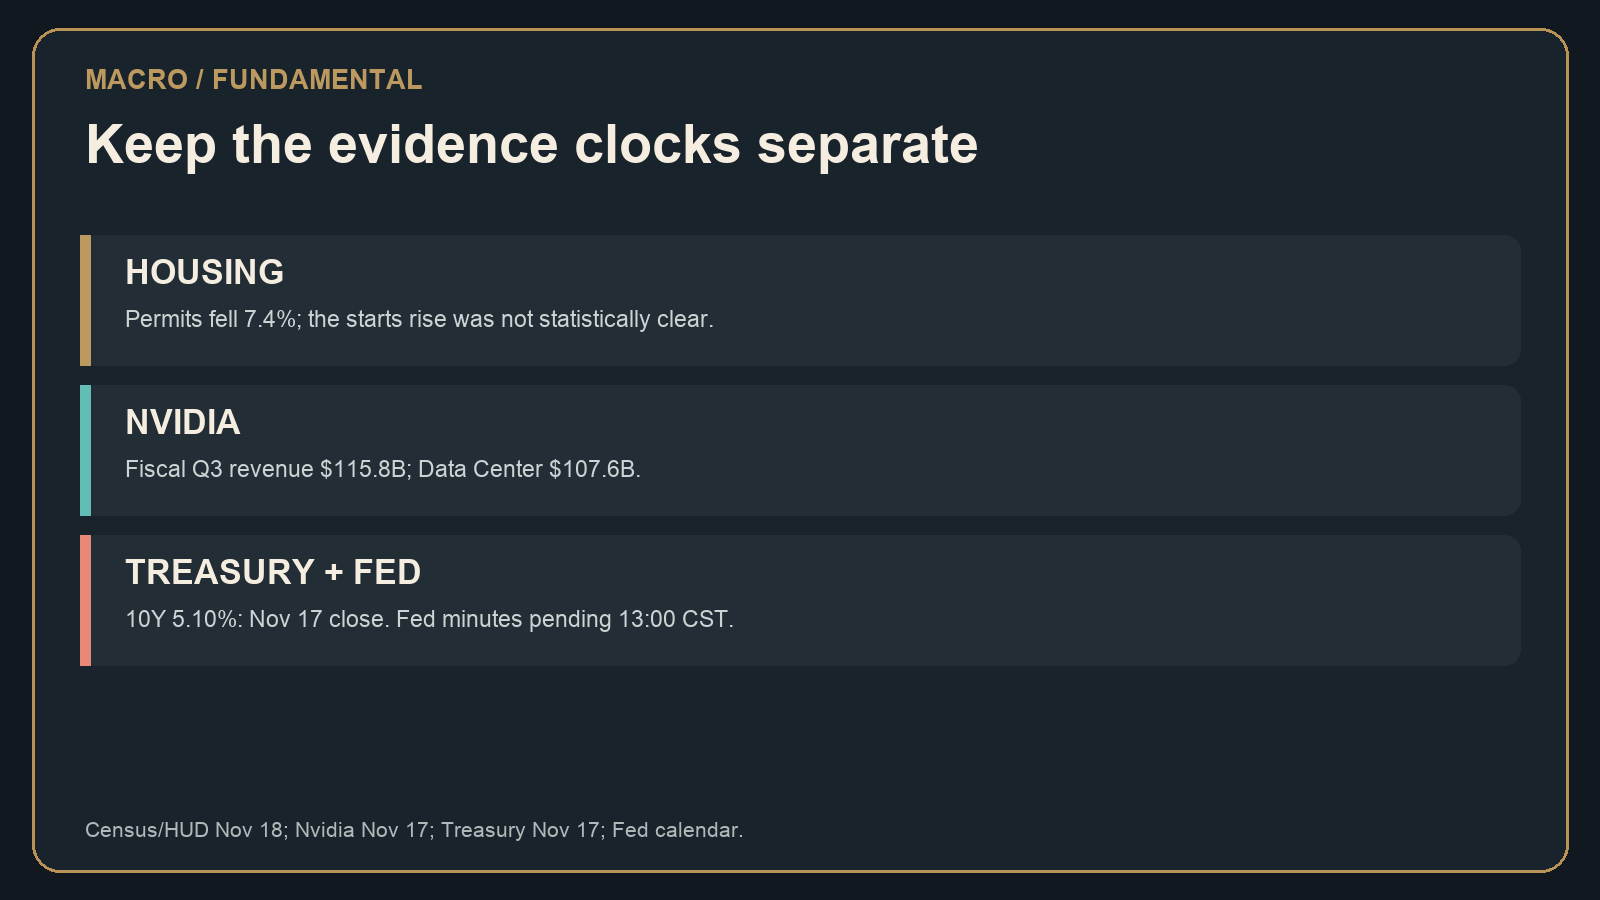
Census/HUD’s 07:30 CST October construction report put permits at a 1.295 million annualized rate, 7.4% below revised September. Starts were 1.309 million, a printed 9.9% monthly rise with a ±16.8 percentage-point margin of error at the agency’s 90% standard, so that starts change is not statistically distinguishable from zero. Permits and starts represent different stages. The report is a dated macro input, not a direct explanation for the late-morning ETF snapshot. Fed minutes at 13:00 CST may shift rate expectations after release; their content is not assumed here.
FUNDAMENTAL | SEPARATE NVIDIA FROM THE GROUP
Nvidia’s November 17 fiscal-third-quarter report showed $115.8 billion revenue and $107.6 billion Data Center revenue. It documents company-level AI infrastructure demand. SMH’s negative fund print does not negate that reported result; the result does not guarantee rising prices for the group. Check peer orders, margins, cash conversion and price behavior before extending the issuer result to the sector.
CROSS-ASSET | KEEP TIMESTAMPS VISIBLE
The Treasury’s latest completed daily par-curve entry available at this review was November 17, with its 10-year at 5.10%. That is not a live late-morning yield. Oil and gold fund proxies have their own last-trade clocks. Asynchronous observations cannot establish that any single cross-asset move caused the ETF divergence. The first visual records the delayed fund sample; the other panels explain the macro evidence boundary and conditional route. They are not native TradingView technical captures.
DECISION ROUTE | DEFENSIVE UNTIL PARTICIPATION REPAIRS
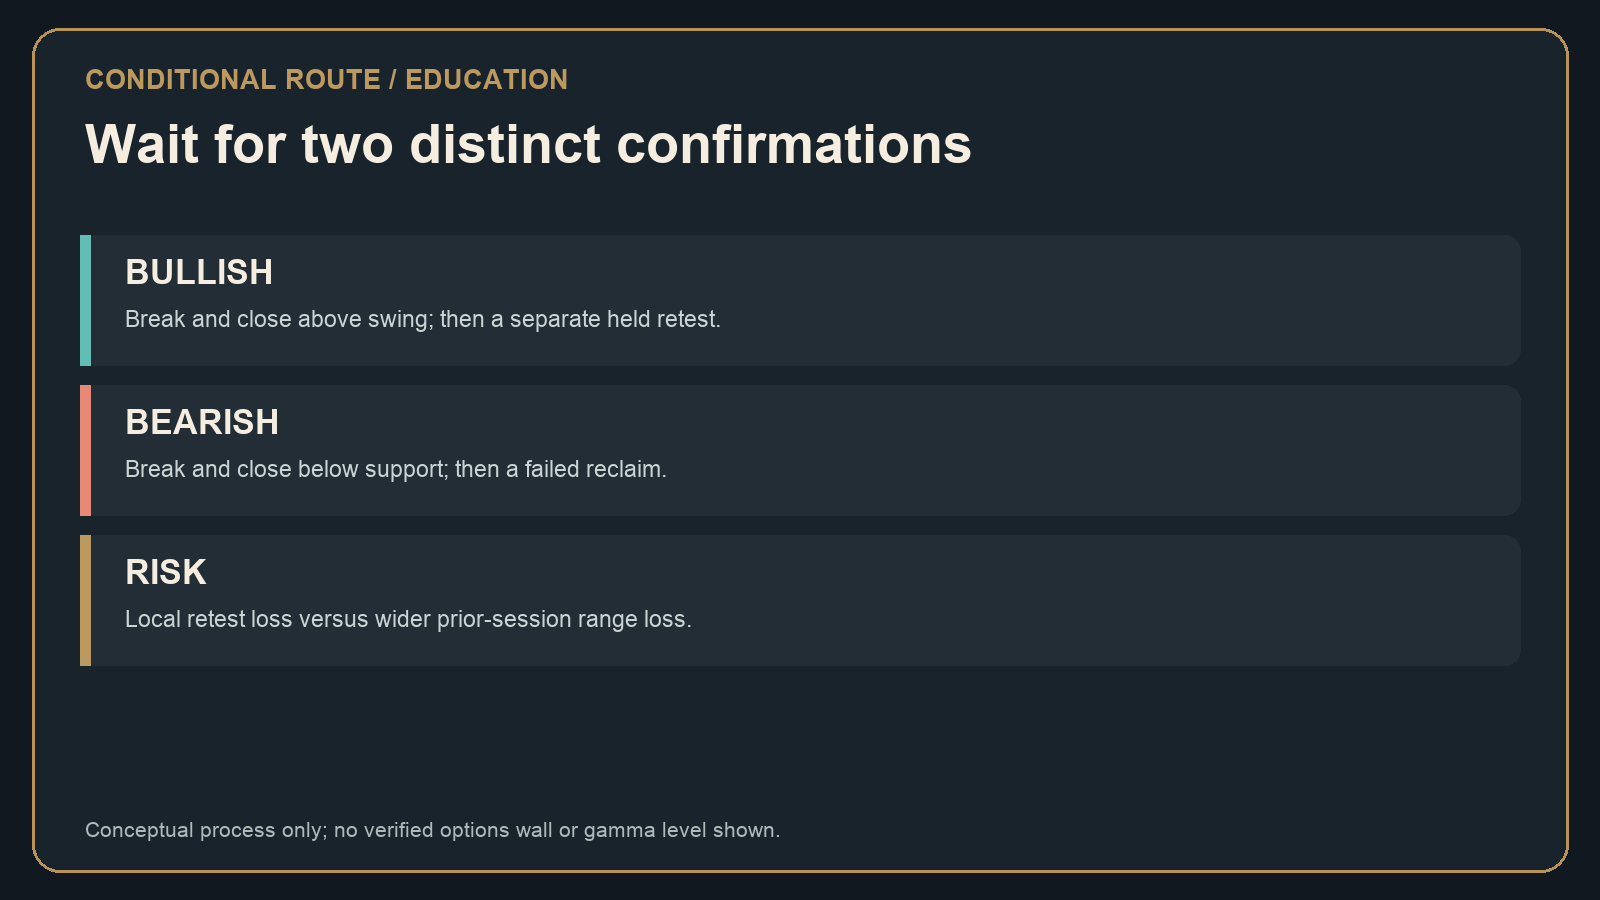
My near-term lean stays defensive on the broad board, with IWM the relative holdout as long as its positive print persists. A bullish route requires a break and close above a clearly observed swing, then a separate held retest, with equal-weight, financial and chip participation improving. Losing that retest locally invalidates the attempted repair; sustained loss of the prior full cash-session range is a wider invalidation. A bearish continuation requires a break and close below observed support, followed by a failed reclaim. The fund snapshot alone satisfies neither confirmation step.
The six-level technical map is incomplete: authenticated Tanuki put- and call-wall definitions and expiry scope, plus two upside and two downside checkpoints, were not verified for this edition. No option wall, gamma flip, trade, fill or result is inferred. Which changes your read first: IWM losing green, or RSP and semiconductors joining a recovery?
Sources and cutoffs: delayed ETF latest trades 10:51:23–10:52:05 CST Nov 18, reviewed about 11:10 CST; U.S. Census Bureau/HUD October New Residential Construction released 07:30 CST Nov 18; Nvidia fiscal-third-quarter investor release Nov 17; U.S. Treasury Daily Par Yield Curve Rates Nov 17; Federal Reserve FOMC calendar, minutes scheduled 13:00 CST Nov 18.