November 18, 2026, 08:42 CST source cutoff. Equity figures are Alpaca IEX feed last trades in liquid ETFs versus each ETF’s November 17 close. They are proxies, not consolidated breadth counts or cash-index prints. Futures, rates and commodity observations came from TradingView market pages around 08:40 CST.
MARKET | THE OVERNIGHT LEAD REVERSES
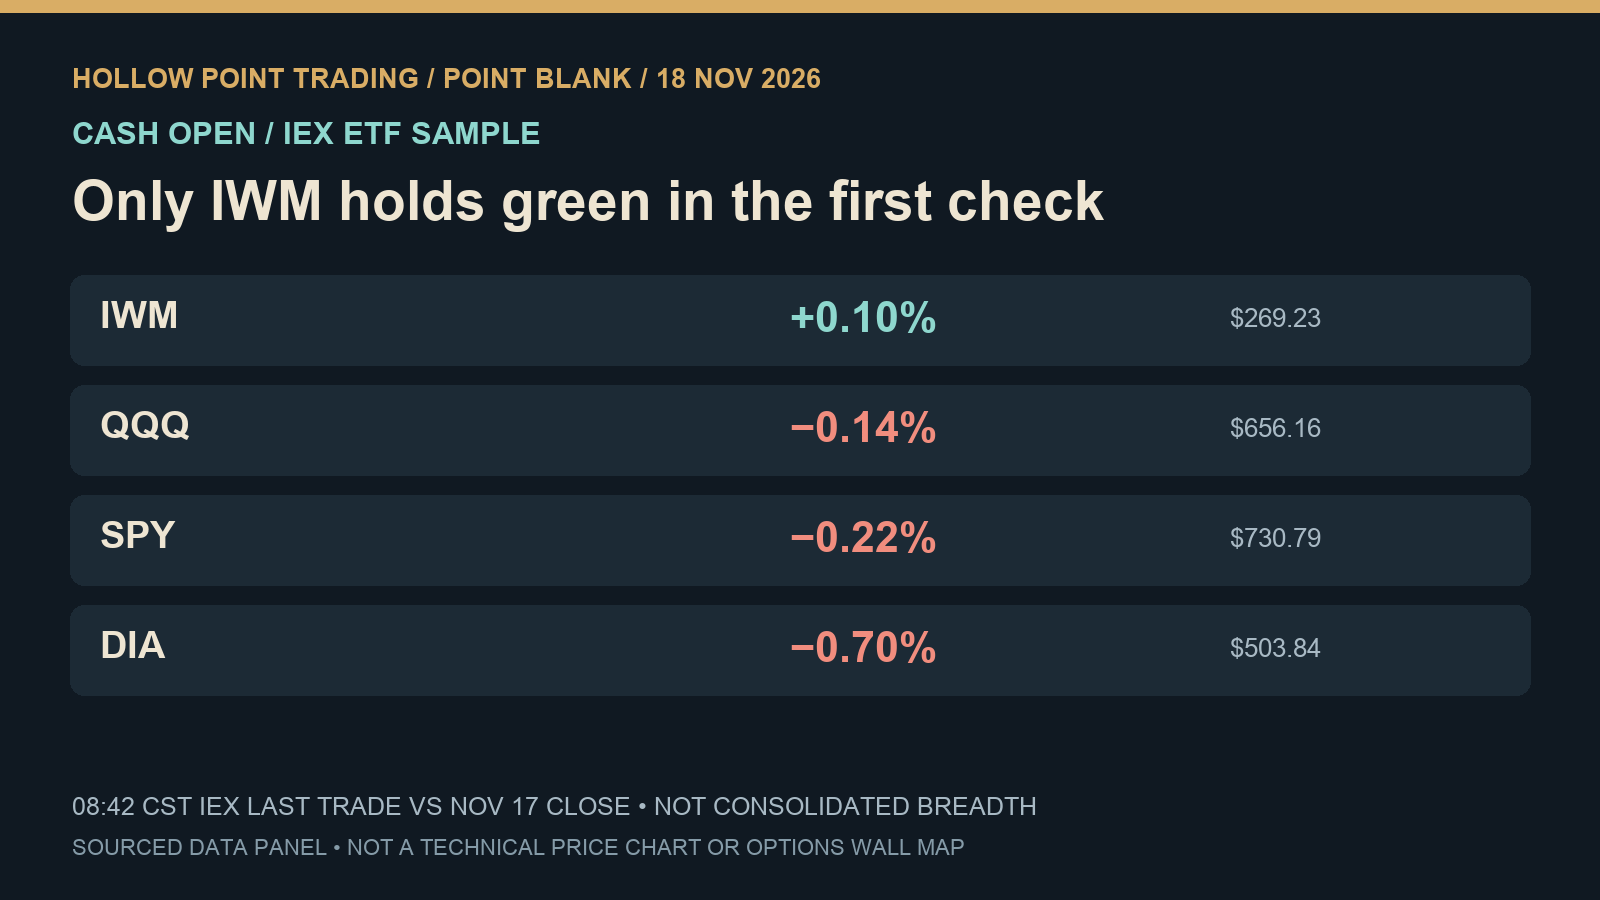
The overnight story was Nasdaq leadership while Russell lagged. Twelve minutes after the cash open, QQQ traded $656.16 (−0.14%) while IWM traded $269.23 (+0.10%). SPY at $730.79 was −0.22%; DIA at $503.84 was −0.70%. IWM alone was green in this four-ETF check. This is a reversal of the earlier leadership order, not proof the whole market has turned higher.
SECTORS | PARTICIPATION IS STILL THIN
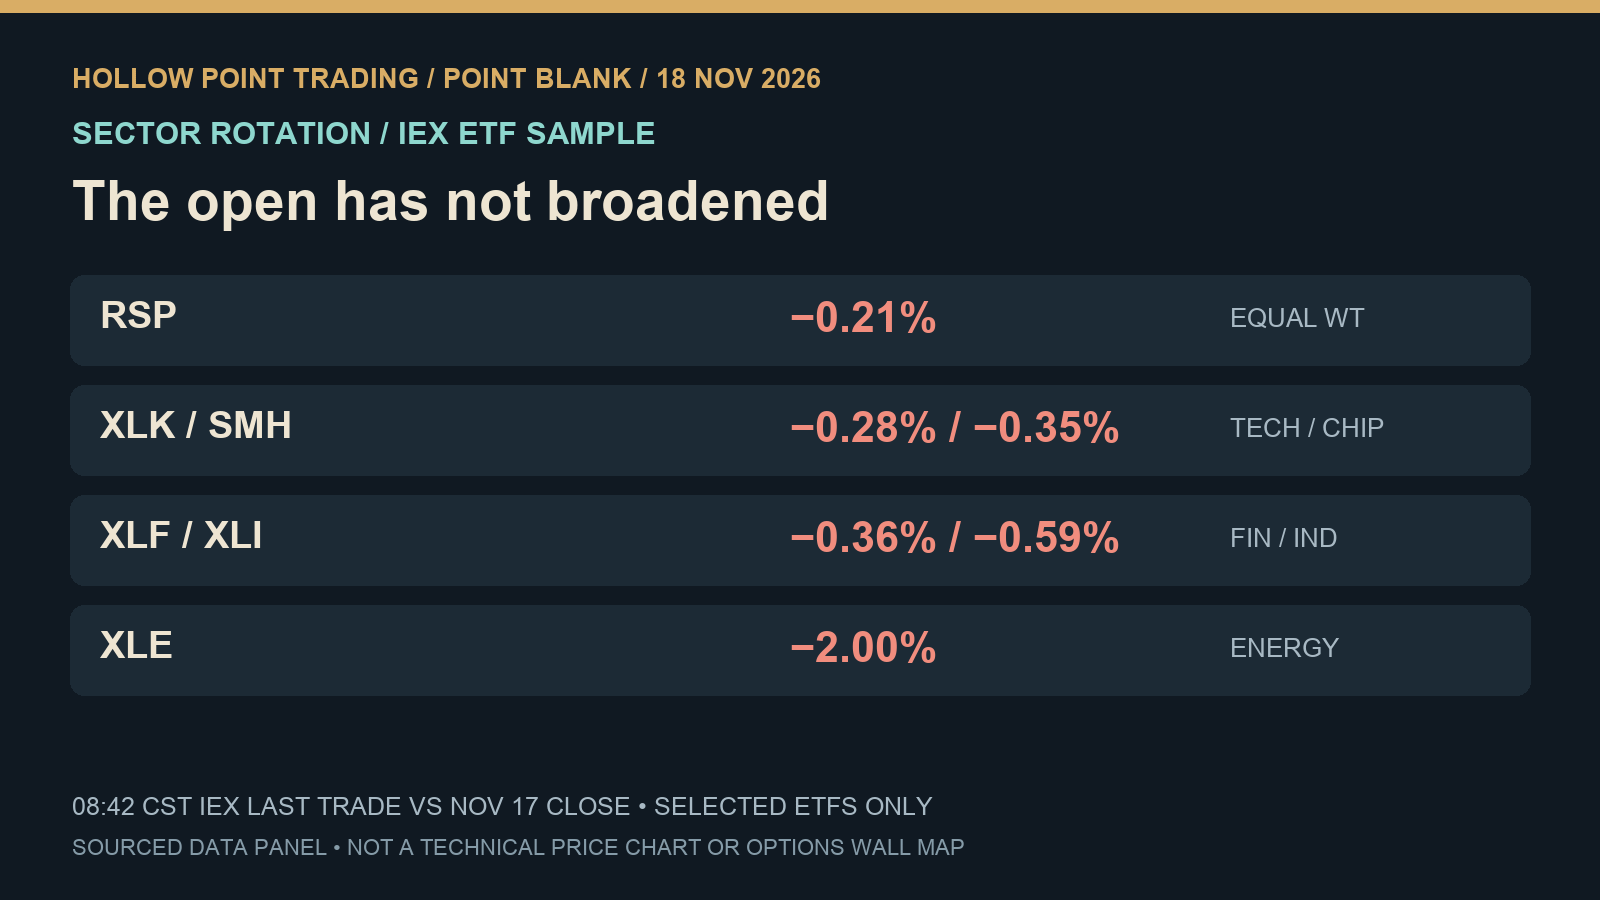
Equal-weight S&P proxy RSP was −0.21%; XLK technology −0.28%, SMH semiconductors −0.35%, XLF financials −0.36%, XLI industrials −0.59%, XLV health care −0.44%, and XLE energy −2.00%. This sampled IEX ETF comparison does not count advancing stocks. Tech and semiconductors slipped below their prior closes even after Nvidia’s strong reported revenue. Energy was the clearest laggard in the sample.
MACRO | HOUSING HAS TWO STORIES
At 07:30 CST, Census and HUD reported October permits at 1.295 million seasonally adjusted annual rate, down 7.4% from revised September, while starts were 1.309 million, up a printed 9.9%. The starts monthly change has a ±16.8% margin of error and is not statistically distinguishable from zero at the agency’s 90% threshold. Permits lead the project pipeline; starts mean work beginning. The split limits any simple growth conclusion. The Federal Reserve’s October 27–28 minutes are scheduled for 13:00 CST and were unreleased at this cutoff.
CROSS ASSETS | CO-MOVEMENT IS NOT CAUSE
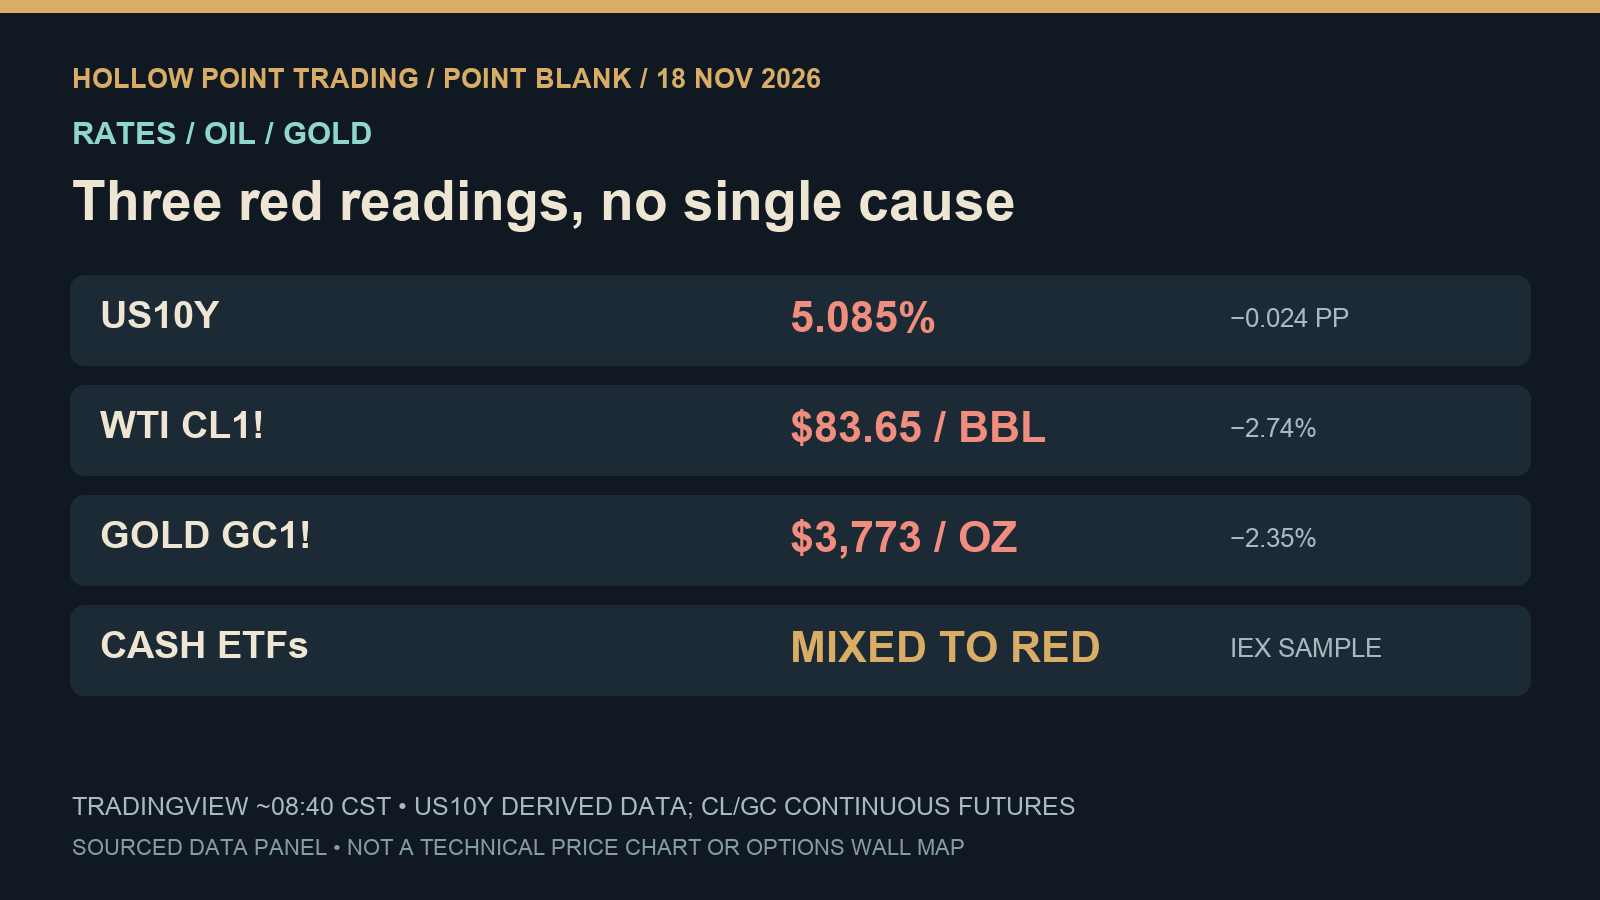
TradingView’s derived US10Y yield was 5.085%, down 0.024 percentage point on the day around 08:40 CST. Continuous WTI CL1! was about $83.65/bbl (−2.74%) and continuous gold GC1! about $3,773/oz (−2.35%). Falling yields, oil and gold occurred beside a mixed-to-red ETF sample; no single cause follows from that observation. Oil weakness is context for XLE, not a demonstrated explanation for every constituent.
FUNDAMENTAL | COMPANY RESULTS ARE NOT MARKET BREADTH
Nvidia reported November 17 fiscal-third-quarter revenue of $115.8 billion, including $107.6 billion in Data Center revenue. Those company-reported figures support a specific AI infrastructure demand story. They do not certify this morning’s semiconductor price action or earnings for banks, builders and small companies.
DECISION ROUTE | WAIT FOR THE NEXT TEST
My near-term lean is cautious/neutral on the broad market. IWM’s green print is constructive, but RSP, SPY, DIA and sampled sectors have not confirmed. A bullish shift needs a break and close above an observed opening swing, then a separate held retest, ideally with RSP and several cyclical groups joining. Losing that retest is local invalidation; a sustained break below the prior full cash-session range is wider invalidation, judged on its own timeframe. The bearish route needs a break and close below observed opening support followed by a failed reclaim. These are conditional process rules, not claimed live chart levels.
Authenticated Tanuki put/call walls, expiry scope and two-up/two-down checkpoints were not verified, so the six-level technical map remains incomplete. The three images are original sourced-data panels, not native TradingView technical captures, option walls or trade signals. No position, fill or result is asserted.
Which changes first: RSP joining IWM above its prior close, or IWM surrendering its early positive print?
Sources: Alpaca IEX stock snapshots 08:41:48–08:42:13 CST November 18; TradingView US10Y, CL1!, GC1! ~08:40 CST; Census/HUD CB26-187 at 07:30 CST; Federal Reserve November calendar; Nvidia November 17 investor release.