November 18, 2026 midmorning cash-session edition. ETF quotes are delayed latest trades from 09:52:58–09:53:00 CST, reviewed at 10:08 CST, versus November 17 closes. They are a historical sample, not live 10:08 prices, index cash closes or a count of advancing securities. The Fed’s October 27–28 minutes are scheduled for 13:00 CST and unreleased at this cutoff.
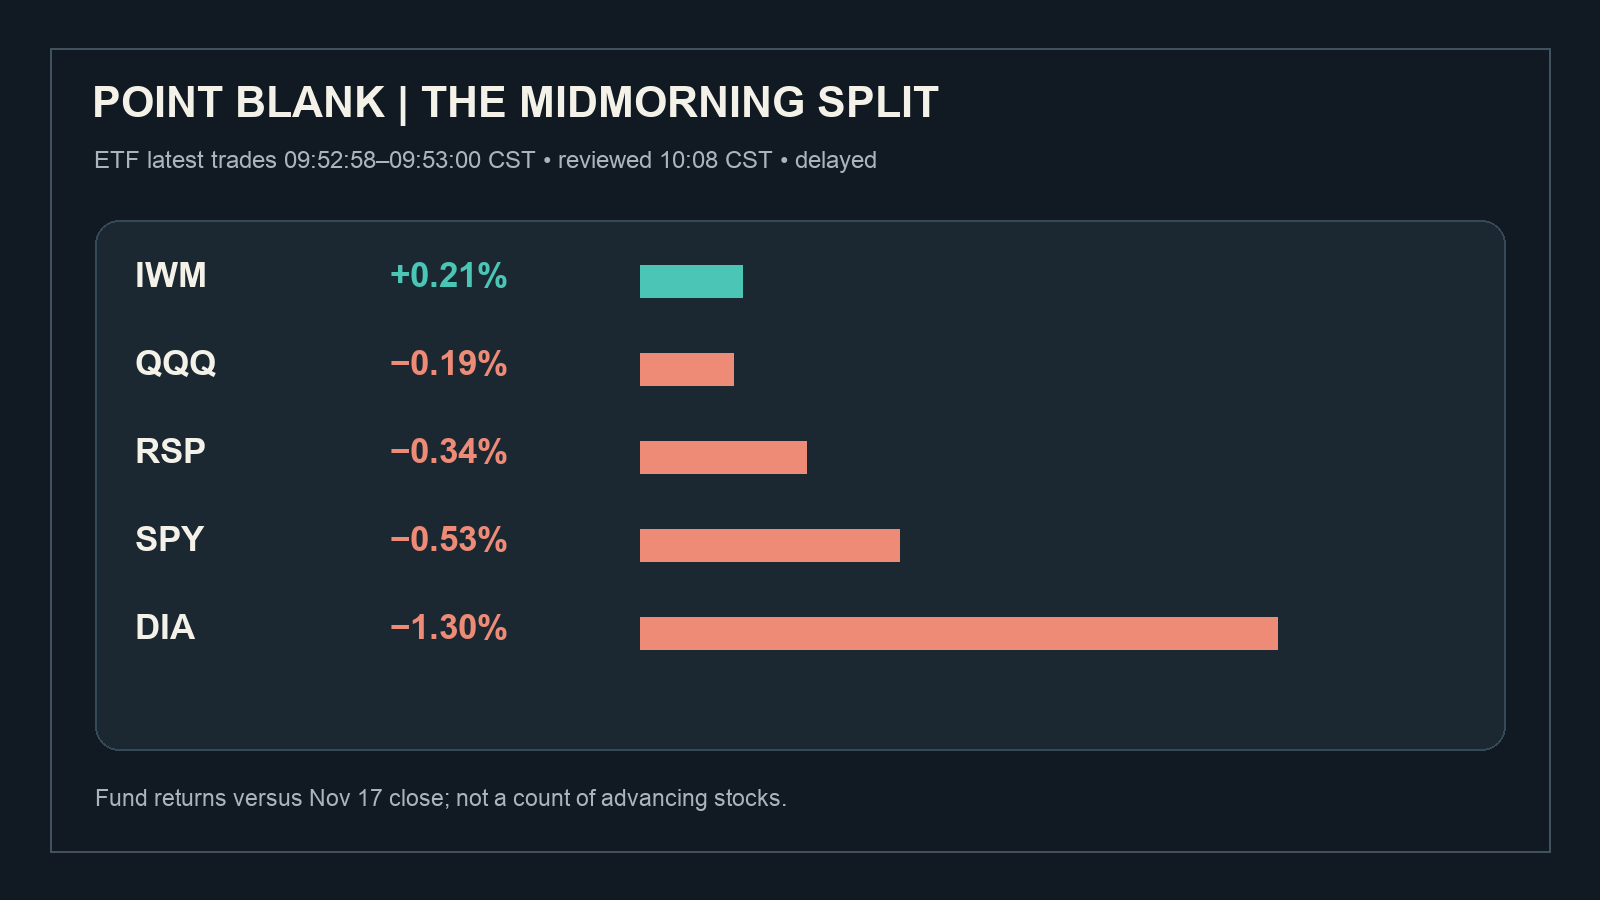
MARKET | EARLIER NASDAQ GREEN HAS DISAPPEARED IN THE SAMPLE
IWM was $269.62 (+0.21%) while QQQ was $655.70 (−0.19%), SPY $728.55 (−0.53%), RSP $215.02 (−0.34%) and DIA $500.74 (−1.30%). At the prior 09:29–09:30 delayed sample, IWM was up 0.71% and QQQ up 0.42%. QQQ changed direction between samples and IWM’s gain narrowed. Equal weight and the Dow remained negative. Small-cap green is a relative holdout, not a confirmed broad advance. A fresh synchronized quote and constituent advance/decline count would be needed to call participation repaired.
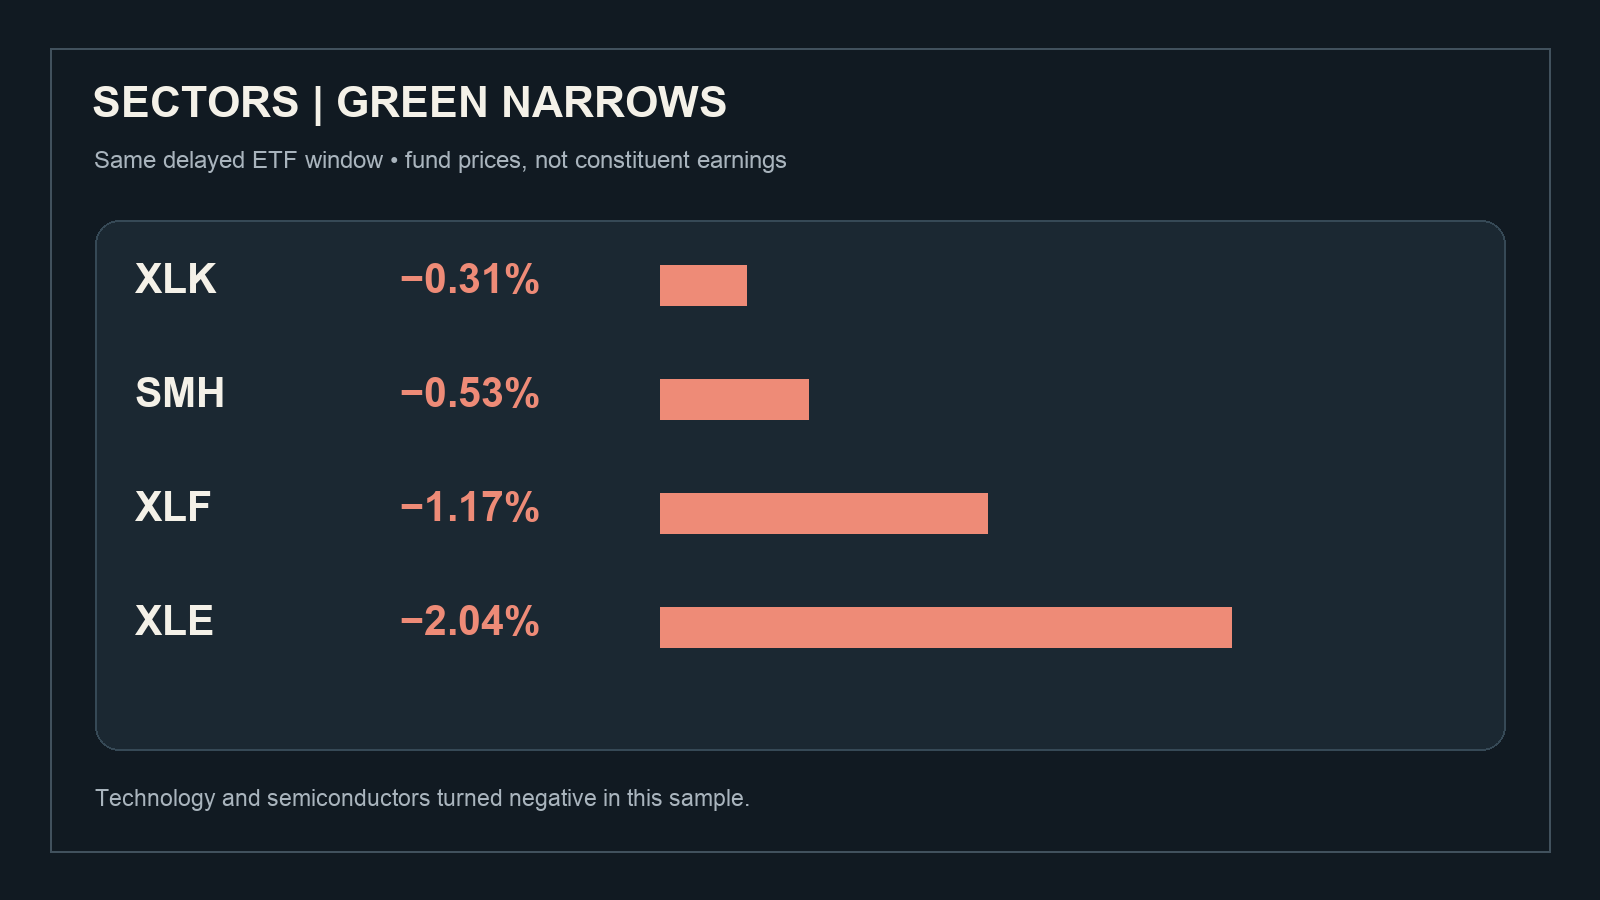
SECTORS | THE TECH BID HAS TURNED NEGATIVE
XLK was $162.76 (−0.31%) and SMH $457.65 (−0.53%) in the 09:53 delayed sample. XLF was $56.40 (−1.17%) and XLE $62.07 (−2.04%). Technology and semiconductors, positive in the earlier sampled window, slipped below prior closes; financials and energy weakened further. Fund moves do not reveal each constituent’s return or prove one news item caused the sector shift. The earlier QQQ/IWM pairing no longer describes this later sample.
FUNDAMENTAL | SEPARATE NVIDIA’S REPORT FROM THIS MORNING’S TAPE
Nvidia’s November 17 fiscal-third-quarter release reported $115.8 billion revenue, including $107.6 billion in Data Center. That is company-level AI infrastructure evidence. SMH’s negative ETF print does not reverse Nvidia’s reported result, and the report does not guarantee the fund stays green. For a durable sector thesis, check peer order books, margins and cash conversion rather than treating one large company’s revenue as a real-time breadth gauge.
MACRO | HOUSING DATA IS A SPLIT SIGNAL
At 07:30 CST, Census/HUD reported October permits at a 1.295 million seasonally adjusted annual rate, down 7.4% from revised September. Starts were 1.309 million, a printed monthly rise of 9.9% with a ±16.8% margin of error at the agency’s 90% standard; that starts change is not statistically distinguishable from zero. Permits are approvals and starts are construction begun. Builder, supplier and lender conclusions need issuer-level demand, backlog and financing evidence.
CROSS-ASSET CHECK | DO NOT BORROW A CLOCK
The ETF snapshot is timestamped; a Treasury-yield page, commodity futures display and fund trade may not share a last-trade clock. Energy’s decline may invite an oil explanation, but concurrent weakness alone does not establish causality. Fed minutes may become a rate catalyst after 13:00 CST; they were unreleased when this sample was reviewed.
DECISION ROUTE | REPAIR REQUIRES MORE THAN A GREEN IWM PRINT
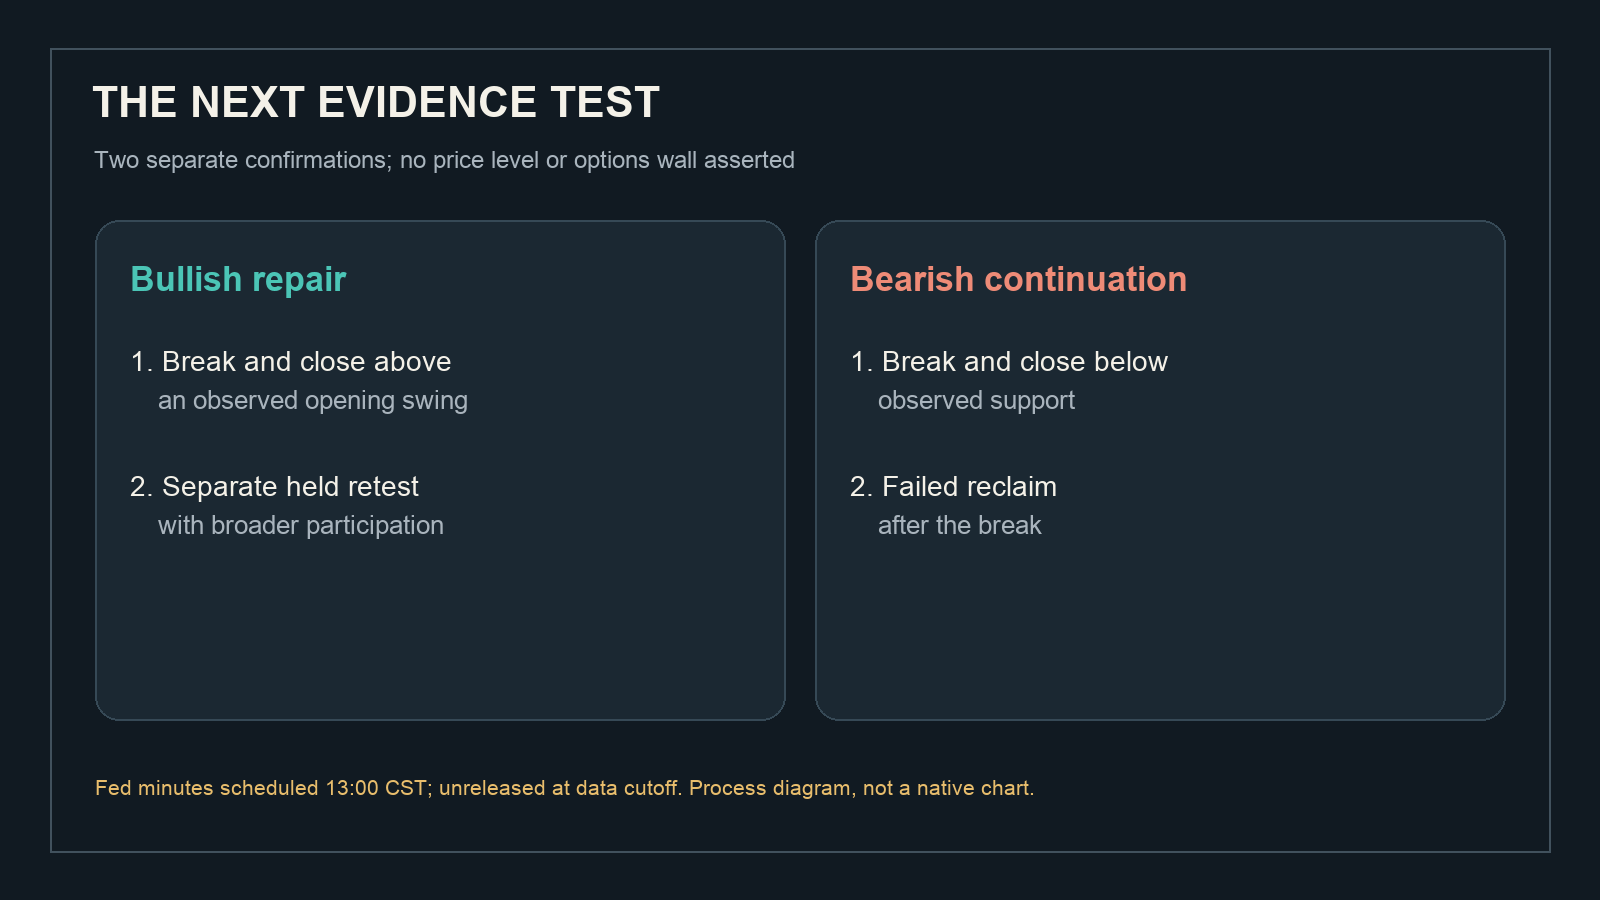
My near-term lean is defensive on the broad board, with a relative watch on IWM while it remains positive. Bullish repair needs a break and close above an observed opening swing, then a separate held retest. RSP, financials and Nasdaq participation would strengthen it. Losing that retest invalidates the local attempt; sustained loss of the prior full-session range is the wider thesis test. Bearish continuation needs a break and close below observed support, then a failed reclaim. A negative ETF snapshot by itself is neither step.
The six-level technical map remains incomplete: authenticated Tanuki put- and call-wall definitions and expiry scope, plus two upside and two downside checkpoints, were not verified here. No wall, gamma flip, position, fill or result is inferred from fund returns. The visuals are explanatory data panels and a process diagram, not native TradingView technical chart captures.
What would signal a more credible repair: IWM holding its lead while equal weight and financials recover, or QQQ reclaiming its prior close first?
Sources and cutoffs: delayed ETF latest trades 09:52:58–09:53:00 CST Nov 18, reviewed 10:08 CST; earlier 09:29–09:30 delayed sample; U.S. Census Bureau/HUD October New Residential Construction CB26-187 released 07:30 CST Nov 18; Nvidia fiscal-third-quarter investor release Nov 17; Federal Reserve November 2026 FOMC calendar.
10:19 CST review of newer delayed trades (10:03:23–10:04:31 CST): IWM $270.08 (+0.38%), QQQ $657.81 (+0.13%), SPY $729.85 (−0.35%), RSP $215.50 (−0.12%) and DIA $501.77 (−1.09%). QQQ recovered above its prior close after the 09:53 sample; IWM remained positive, but equal weight and the Dow still lagged. XLK was essentially flat at $163.27 (+0.01%), SMH $458.74 (−0.30%), XLF $56.50 (−1.00%) and XLE $61.83 (−2.41%). The accompanying boards preserve the earlier 09:53 sample for comparison; they do not depict this later update. This is a two-sample intraday whipsaw, not proof of a settled breakout.
10:29 CST prepublication check of delayed latest trades stamped 10:13:05–10:13:57 CST: QQQ $656.27 (−0.10%) had slipped back below its prior close; IWM $269.61 (+0.21%) stayed green. SPY was $728.90 (−0.48%), RSP $215.12 (−0.30%), DIA $501.19 (−1.21%), XLK $163.01 (−0.15%), SMH $457.39 (−0.59%), XLF $56.43 (−1.12%) and XLE $61.86 (−2.37%). These are delayed, asynchronously stamped trades. The alternating QQQ sign reinforces the uneven, unconfirmed breadth assessment; the boards remain the earlier 09:53 historical sample.