
There's a line on the chart that a $40 billion fund and a guy trading one contract from his kitchen are both staring at. Same line. Same number. That almost never happens in markets, where the big players usually see a different game than you do. They have faster data, deeper books, and models you'll never touch. But VWAP is the great equalizer, because it answers a question everybody — retail and institutional — is asking at the same time: is the average buyer today winning or losing?
If you learn to read one indicator properly this year, make it this one. Not because it's magic. Because it's where the size actually lives. Most indicators describe price. VWAP describes participation — and participation is what moves markets. A line that tells you where the heavy money is leaning is worth more than a hundred oscillators that only tell you where price has been.
This guide builds VWAP from the ground up: the math so you're never mystified by it, the reason it works so you're not trading a superstition, the two flavors and when each one matters, the bands, a five-step read you can run on any chart, a stack of fully worked examples with real numbers, how it behaves across trend, chop, and high-volatility regimes, how it lives on multiple timeframes at once, how to stack it with your other tools, the twelve mistakes that quietly bleed accounts, how the pros use it differently than beginners, a FAQ, and a cheat-sheet you can pin to the wall. By the end you'll be reading the same page as the desks — and you'll know what to do with it Monday morning.
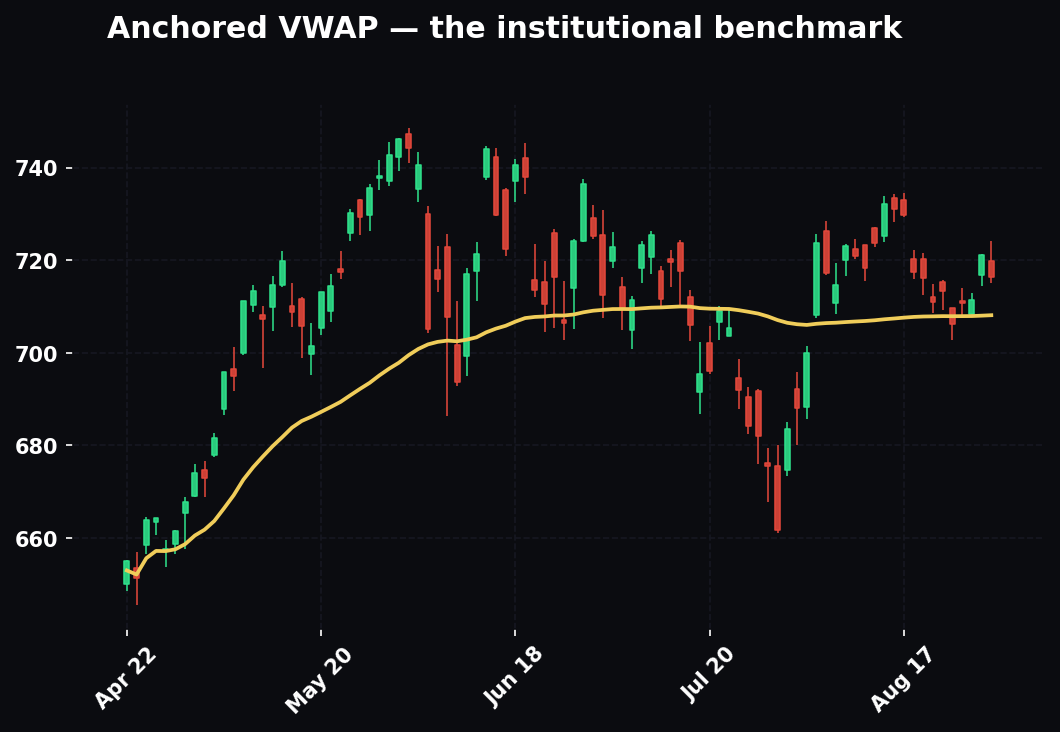
What VWAP Actually Is
VWAP stands for Volume-Weighted Average Price. Strip the jargon: it's the average price of every share or contract traded so far, weighted by how much traded at each price.
That "weighted" part is the whole point. A normal moving average treats every bar the same — a bar where 10 contracts traded counts exactly as much as a bar where 10,000 traded. VWAP doesn't. It cares where the volume happened. A price level where a huge amount changed hands pulls VWAP toward it hard; a price where almost nothing traded barely moves it. VWAP is the market's honest confession about which prices it actually respects, because it only listens to prices that had money behind them.
The Math, So You're Never Mystified By It
For each bar you take the typical price — (high + low + close) ÷ 3 — multiply it by that bar's volume, and keep a running total. You also keep a running total of the volume itself. VWAP at any moment is:
VWAP = (running total of price × volume) ÷ (running total of volume)
So if in the first three 1-minute bars of the day NQ trades:
- Bar 1: typical price 20,000, volume 1,000 → 20,000,000
- Bar 2: typical price 20,010, volume 3,000 → 60,030,000
- Bar 3: typical price 20,005, volume 500 → 10,002,500
Total price×volume = 90,032,500. Total volume = 4,500. VWAP = 90,032,500 ÷ 4,500 = 20,007.2.
Notice Bar 2 dragged VWAP up toward 20,010 far more than Bar 3 pulled it back, even though Bar 3 was more recent — because Bar 2 had six times the volume. That's the mechanism. Recency doesn't win; participation wins. That single property is why VWAP behaves differently from every EMA on your chart, and why it's harder to fake out.
Let's push the example one bar further to cement it. Say Bar 4 prints a violent spike: typical price 20,040, but on thin volume of just 200 contracts. That's 20,040 × 200 = 4,008,000 added to the numerator, and 200 added to the denominator. New numerator = 94,040,500; new denominator = 4,700; new VWAP = 20,008.6. A 30-point price spike moved VWAP barely one and a half points, because the market didn't actually trade much up there. An EMA would have lurched toward that spike. VWAP shrugged. This is exactly why VWAP filters out low-conviction stop-runs and headline reflex spikes that fool trend-following averages — it demands volume before it believes a move.
The Cumulative Property — Jumpy at the Open, Immovable by Midday
One more thing to lock in: VWAP is cumulative from an anchor point. Session VWAP resets at the open and rebuilds all day. Early in the session it whips around because there's little volume to stabilize it — the denominator is small, so each new bar has real leverage over the average. By midday it's heavy and slow, because it's now the average of millions of contracts; one more bar barely moves it. By the last hour it's practically a fixed wall.
This isn't a quirk to work around — it's a feature you schedule your trading around. VWAP is jumpy at 8:35 and near-immovable at 1:00. A rejection off VWAP at 9:05 might just be the line whipping through a light-volume zone; the same rejection at 12:30 is price bouncing off a level backed by hours of accumulated size. Same line, completely different weight of evidence. The single most common way beginners get chopped up is treating an unstable morning VWAP with the same trust they'd give an anchored, midday one. The line earns its authority as the session ages.
Typical Price vs Close — A Small Detail That Matters
Most platforms build VWAP off the typical price (H+L+C)/3, not the close. That's deliberate: using the full range of each bar captures where trading actually occurred, not just where the bar happened to settle. Some traders switch it to HLCC/4 (weighting the close a little more) or to the raw close. The differences are usually tiny, but on a fast, wide-range instrument like NQ they can be a point or two — enough to matter when you're placing a stop right at the line. Know which one your platform uses and stay consistent, because a VWAP off the close and a VWAP off the typical price will disagree slightly, and you don't want that disagreement showing up as a mystery on your chart.
Why Funds Benchmark to It — The "Why It Works"
Here's the part most tutorials skip, and it's the part that makes VWAP tradeable instead of just decorative.
When a pension fund or a mutual fund needs to buy 400,000 shares of a stock, they can't just hit the market — they'd move the price against themselves and everyone would front-run them. So they feed the order in slowly over hours, often through an algorithm whose explicit goal is: fill at or better than the day's VWAP.
This isn't a preference. It's how the desk is graded. The execution trader's performance is literally measured against VWAP. Bought below VWAP on a buy order? Good fill, you beat the benchmark. Bought above it? You underperformed, and someone asks why. Bonuses, capital allocation, and whether that trader keeps the account all trace back to a number: their average fill versus VWAP, measured in basis points, every single day.
The Magnet Made of Other People's Incentives
Sit with what that means. A massive, price-insensitive pool of buying pressure is programmed to get more aggressive when price dips below VWAP (cheap relative to benchmark — buy more) and to ease off when price runs above it (expensive — wait). That's a mechanical, self-reinforcing reason price gets pulled back toward VWAP on quiet, trend-less days. The line isn't predictive voodoo. It's a magnet made of other people's incentives.
Think about the feedback loop. Price dips below VWAP → benchmark-buying algos see a bargain relative to their grade → they lean in harder → their buying lifts price back toward VWAP → the pull you predicted actually happens. And it's not one algo; it's dozens of desks all running the same logic against the same public number. Their collective self-interest builds the wall you're trading off of. That's why VWAP reversion on a balanced day isn't a hopeful pattern — it's a crowd of professionals mechanically obligated to defend the mean.
And It Cuts the Other Way
It cuts the other way too. On a strong trend day, price accepts being far from VWAP and never comes back — because the institutional flow is one-directional and the benchmark chasers are all on the same side. If a fund has to buy 400,000 shares into a market that's ripping higher on real news, "wait for a dip below VWAP" is a losing instruction — the dip never comes, and they fall further behind the benchmark chasing it. So they capitulate and buy strength, which is the trend, which drags VWAP up underneath price rather than pulling price back down to VWAP. The benchmark that was a magnet on Tuesday becomes a launchpad on Wednesday.
The distinction between those two regimes — reversion toward VWAP versus acceptance away from it — is the entire skill. We'll get there. But hold onto the core insight: VWAP works because it's not describing sentiment, it's describing where the benchmark-driven money is obligated to lean. That's a structural edge, not a hopeful pattern. It's built into the plumbing of how large orders get executed, and that plumbing doesn't change with your opinion.

Session VWAP vs Anchored VWAP
There are two flavors, and confusing them is the number-one beginner error.
Session VWAP
Session VWAP (usually just "VWAP") anchors to the start of the trading session and resets every day. This is the default line on TradingView and the one the intraday algos are benchmarked to. It answers: is the average participant green or red on the day? It's the right tool for day trading and intraday bias.
A subtlety most people miss: which session? For futures like NQ, VWAP can anchor to the full 24-hour globex session (6:00 PM ET the prior evening) or to the regular cash-hours open (9:30 AM ET). Those two lines can sit points apart on an active morning, and they tell you different things. The globex VWAP is the average of everyone since last night's electronic open, including thin overnight trade; the cash-session VWAP is the average since the real liquidity showed up. For most intraday US-equity-index trading, anchoring VWAP to the cash open (9:30) gives you the line the daytime desks actually benchmark against. Pick your session deliberately — don't just accept the default and wonder why your VWAP doesn't match the levels price keeps respecting.
Anchored VWAP
Anchored VWAP (AVWAP) lets you choose the anchor — the starting point of the calculation. Instead of "since the open," it's "since [the moment that mattered]." You drop the anchor on a specific candle and VWAP builds forward from there, ignoring everything before it.
Why is that powerful? Because it answers: what is the average price everyone who's been in this move since [the event] is holding? And that number is a real, tradeable level — it's the line between the crowd that entered at the event being collectively in profit or in loss. Cross below it and the average bag from that event is now underwater. That flips psychology, and psychology flips flow. A trader who's green sits patiently; a trader who's just gone red starts looking for the exit. AVWAP is the exact price where a whole cohort of participants flips from one of those states to the other — which is why price so often reverses right there.
The Anchors That Matter Most
- Earnings. Anchor to the first candle after an earnings report. Everyone who's traded the stock on the "new information" is measured against this line. It's often the cleanest support/resistance on the chart for weeks, because earnings is the moment the market re-rated the whole thesis.
- A major swing high or swing low. Anchor to the high of a big rally or the low of a capitulation. AVWAP from a significant low is the average entry of every bull since the bottom — a natural support shelf. AVWAP from a significant high is the average cost of the trapped bulls — a natural ceiling that gets sold into.
- The year open / quarter open / month open. Anchor to Jan 1 (or the first trading day). "Year-to-date VWAP" is a genuine institutional bias line — above it the year's average buyer is green, below it they're red. Fund performance is often measured YTD, so this line has real career-stakes weight behind it.
- IPO / first day of trading. For a newly public company there's no prior history, so AVWAP from the IPO candle is the reference price everyone who's ever owned it is measured against. Watch how names behave the first time they reclaim or lose it — those are some of the cleanest levels in the entire market.
- A gap, a news catalyst, a Fed day, a big-volume breakout bar. Any moment where the market got new information and repriced. The bigger the volume on the anchor bar, the more meaningful the resulting AVWAP.
The mental model: session VWAP is for today's fight; anchored VWAP is for the war that started at the event. You want both on the chart. Session VWAP tells you who's winning right now; anchored VWAP tells you who's been winning since the last thing that actually changed the story.
How Many Anchored VWAPs Is Too Many?
A practical warning: it's easy to drown your chart in anchored VWAPs until it looks like a bowl of spaghetti and every price has some line near it. That's not confluence, that's noise. Keep it disciplined — three or four anchors that each represent a genuinely significant event: the most recent earnings, the most significant swing (high or low, whichever is in play), and the relevant period open (year or quarter). If you can't say in one sentence why an anchor matters, delete it. The power of AVWAP comes from each line representing a real cohort of trapped or profitable participants. A line with no story behind it just clutters the read.
VWAP Bands (Standard Deviation Envelopes)
VWAP alone tells you the average. The bands tell you how stretched price is from that average — and stretch is where the trades are.
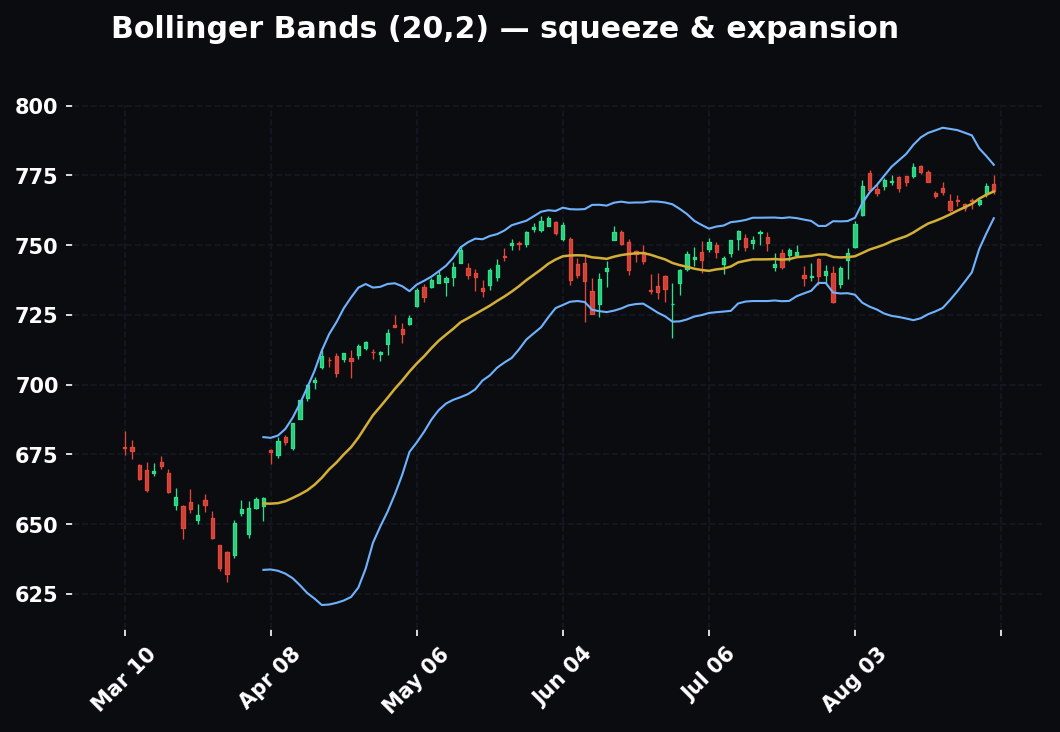
The bands are standard-deviation envelopes drawn above and below VWAP, usually at 1, 2, and sometimes 3 deviations. In plain English: they measure how far price has wandered from the volume-weighted mean relative to how far it normally wanders that day. The band width breathes — it's wide when the day is volatile, tight when it's coiled. That breathing is itself information: bands that are pinching in tell you the day is compressing and a range is forming; bands flaring open tell you volatility just expanded and the character of the day changed.
Reading the Deviations
Rough intuition, not a law: price spends most of its time inside the 1st deviation band. Reaching the 2nd deviation means it's genuinely extended — on a range/reversion day, the 2σ band is where fades set up. The 3rd deviation is a true outlier, often a spike into a stop run or news, and a place you respect rather than blindly fade.
The bands do two jobs at once, and this is the beautiful part:
- On a reversion day, a tag of the 2σ band that fails to hold is a fade signal — price is stretched and the rubber band snaps back to VWAP.
- On a trend day, price rides the 1σ–2σ band on the trend side and never comes back to VWAP. The same band that's a fade line on Tuesday is a trend-following pullback-buy line on Wednesday.
So the bands don't tell you what to do by themselves. They tell you how far you are from the mean, and the regime tells you whether that distance is an opportunity to fade or a reason to hold the trend. Reading which regime you're in is the job — and it's the difference between a trader who thinks VWAP bands are a broken indicator and one who understands they were never a standalone signal in the first place.
The Band-Ride Tell
Here's a professional read hiding inside the bands: on a genuine trend day, watch how price behaves at the 1σ band on the trend side. If every pullback stops at the 1σ band and turns back up (in an uptrend), the band is acting as dynamic support and you have a strong, orderly trend — buy those 1σ touches. The moment price finally closes back through VWAP after riding the upper band all morning, the trend character has broken and the reversion players are back in charge. The 1σ band ride, and its eventual failure, is one of the cleanest regime-change signals VWAP offers.
How to Read It, Step by Step
Here's the actual sequence to run every time you pull up a chart. Do them in order — the order matters, because each step filters the next.
Step 1 — Which side of VWAP is price on? This is your intraday bias in one glance. Above session VWAP, the average buyer today is green and control is with the bulls; you favor longs. Below it, favor shorts. Don't overthink this first read — it's the coarse filter. Fighting it means fighting the benchmark flow, and the benchmark flow has more money than you.
Step 2 — What's VWAP's slope? Flat VWAP = balanced, rotational day → reversion tactics (fade the bands back to VWAP). Rising or falling VWAP at a clear angle = trend day → acceptance tactics (buy pullbacks to VWAP/1σ in an uptrend, sell rallies to VWAP/1σ in a downtrend). Slope changes everything. A flat VWAP and a 30-degree rising VWAP demand opposite playbooks even if price is in the exact same spot.
Step 3 — Reversion or acceptance? Watch what price does at VWAP. Does it hit VWAP and bounce cleanly (reversion — VWAP is a wall)? Or does it slice through VWAP and keep going, then use the other side as support/resistance (acceptance — the market has repriced)? A clean rejection is a trade toward the mean. A decisive break-and-hold through VWAP is a signal the regime just flipped. The retest is where the truth comes out: price that breaks VWAP and then holds the new side on a retest has genuinely accepted; price that pokes through and snaps back has not.
Step 4 — Where are the bands? Is price mid-range (no edge, wait) or stretched to 2σ (edge, if the regime supports it)? Extended into 2σ on a flat-VWAP day is a fade; riding the 1σ on a sloped-VWAP day is a trend hold. If price is sitting right at VWAP with no stretch either way, there's simply no edge yet — the honest read is "wait."
Step 5 — What anchored VWAPs are near? Pull up your earnings anchor, your swing-low anchor, the year-open anchor. When session VWAP lines up with an anchored VWAP at the same price, that's confluence and it's where you want your entries. A band tag that also happens to coincide with an earnings AVWAP is a far higher-conviction spot than a band tag in empty air.
Run those five steps and you have a plan before you've drawn a single trendline. Side, slope, behavior, stretch, confluence — five questions, thirty seconds, and you know whether you're fading, following, or waiting.
Worked Example One — The Reversion Fade
NQ opens at 20,000. First hour is choppy — no direction, VWAP goes flat and sits at 20,005. Classic balance day. Steps 1 and 2 already tell you the mode: price oscillating around a flat line means reversion, not trend.
Around 10:15 a headline pops and NQ spikes to 20,075, stabbing right into the 2σ upper band at 20,072. Volume on the spike is a burst, then dries up on the next two bars — a shooting-star candle prints at the high, closing back at 20,058. That volume-dry-up at the band edge is the tell: the move was a reflex, not real acceptance. Remember the math from earlier — a thin spike barely moves VWAP, which is exactly why VWAP stayed pinned at 20,005 while price was 70 points away. Price is stretched; the mean didn't budge.
The setup: flat VWAP (reversion regime, Step 2) + price stretched to 2σ (Step 4) + reversal candle (Step 3 says no acceptance). Short 20,055. Where's the stop? Above the 2σ band and the spike high — say 20,080 (25 points of risk). Where's the target? The magnet: VWAP at 20,005 for the first target, and if the day stays heavy, the lower 1σ band around 19,985 for the runner. From 20,055 to 20,005 is 50 points — a 2:1 to first target, and the runner to 19,985 gives you 70 points, a clean 2.8:1. That clears the HPT 1:3 minimum on the runner and lets you bank partials at VWAP.
Price drifts back, tags 20,006, you take half. It grinds to 19,988, you're out. The bands gave you the stretch, VWAP gave you the target, discipline banked it. Notice what did the work: not a magic line, but a stretched-from-mean reading on a day whose regime supported reversion, confirmed by price refusing to accept the higher prices.
Worked Example Two — The Anchored Reclaim
A stock — call it a large-cap tech name — reports earnings and gaps down hard. The first post-earnings candle's high is $182. You drop an anchored VWAP on that candle.
For two weeks the stock trades under that AVWAP, which slopes gently down from $182 to about $176. Every rally into the falling AVWAP gets sold — the average earnings-reaction buyer is still underwater, and they sell into strength to get out flat. This is the AVWAP acting as a ceiling, exactly as theory predicts. Each failed rally at the line is another cohort of trapped buyers getting their "get me out at breakeven" wish and adding to supply.
Then one morning, on a broad-market up day and rising volume, the stock pushes through the AVWAP at $176 and — critically — the next few candles hold above it, using $176 as support on the retest. That's the reclaim. The trapped bulls are now green; the pressure that was selling every rally just evaporated. The retest is the whole trade — anyone can watch price poke above a line; the edge is waiting for price to come back, kiss the line from above, and hold.
The setup: AVWAP reclaim with a hold on the retest. Long $176.40 on the successful retest. Stop below the reclaimed line and the retest low — $174.60 (about $1.80 risk). Target: the next overhead anchored VWAP (from the prior swing high) sitting near $182, plus the gap-fill objective. $176.40 to $182 is $5.60 of reward against $1.80 of risk — better than 3:1. The anchor did the work; you just waited for price to prove the flip.
Worked Example Three — The Trend-Day Pullback Buy
This is the one that saves beginners from the deadliest VWAP mistake: fading a trend. NQ gaps up on a strong overnight and opens at 20,200. From the first bar, VWAP builds with a clear upward slope. By 10:00 VWAP is rising through 20,180 and price is riding the 1σ band up around 20,260. Step 1: price above VWAP. Step 2: VWAP sloping up hard. This is acceptance, not reversion — the fade is off the table.
Around 10:40 price pulls back. A beginner sees "extended, fade it." A reader sees a trend day and asks: where does the pullback stop? Price dips to 20,205 — the rising 1σ band on the lower side / VWAP itself, which have converged there as the bands ride up under price. A hammer prints and volume picks up on the turn. That's the trend-day pullback-to-VWAP buy.
Long 20,210. Stop below VWAP and the pullback low, 20,185 (25 points). The target isn't a fixed magnet — on a trend day you target the prior high and then trail. Price resumes, takes out 20,260, and you trail under each new higher low, riding the upper band into 20,340 before a close back under VWAP finally stops you out for +100+. From 20,210 risking 25 to make 100+ is a 4:1 that only existed because you read the slope and refused to fade a rising VWAP.
Worked Example Four — The Failed Reclaim (When It Doesn't Work)
Honest trading education shows the losers too. Same setup as Example Two, but it fails — and knowing what failure looks like keeps you from marrying a broken thesis.
A name trades under its earnings AVWAP at $50.20. One morning it pushes through to $50.60. You're tempted to buy the reclaim. But watch Step 3 carefully: the push through comes on declining volume, and the very next bar closes back at $50.05 — below the line. There was no hold on the retest; price rejected the reclaim immediately. That's a failed reclaim, and it's actually a short signal: the trapped sellers just proved the line still caps them.
If you'd bought the poke at $50.55 with a stop at $50.00, you're out for a 55-cent loss — small, because you defined risk at the line. The lesson: the reclaim is only valid with the hold on the retest. Price above the line for one bar is a rumor; price retesting the line from above and holding is the confirmation. Trade the confirmation, not the rumor, and when the confirmation fails, take the small loss and consider the trade in the other direction.
VWAP Across Market Regimes
The single most valuable skill with VWAP is matching your tactics to the regime. Here's how the line behaves in each, and what it demands of you.
Trending Regime
On a trend day, VWAP slopes clearly and price stays on one side of it for hours. The mean is not a magnet here — it's a floor (uptrend) or a ceiling (downtrend) that price uses for pullback entries. Pullbacks to VWAP or the trend-side 1σ band are buys in an uptrend, sells in a downtrend, not fades. The tell you're in this regime: price fails to cross VWAP on multiple attempts, the band on the trend side keeps getting ridden, and VWAP's slope is steady. The mistake that kills accounts here is treating the 2σ band as a fade level — you'd be shorting into the exact one-directional institutional flow the band is measuring.
Ranging / Balanced Regime
On a balanced day, VWAP is flat and price rotates around it like a pendulum. This is reversion heaven: fade the 2σ bands back to VWAP, fade VWAP back to the opposite band, and repeat until the range breaks. The tell: price crosses VWAP repeatedly and easily, neither band gets ridden, and the whole structure looks like a horizontal channel with VWAP down the middle. The mistake here is chasing breakouts — most "breakouts" on a balance day are just a tag of the outer band that snaps right back. Sell the extremes, buy the extremes, respect that the day wants to rotate.
High-Volatility Regime
On a high-vol day — a Fed decision, a CPI print, a geopolitical shock — the bands blow wide open and VWAP itself can get dragged around fast. Here VWAP is less reliable as a precise level and more useful as a directional anchor. The stretches to 2σ and 3σ are enormous, and fading them is playing with fire because a genuine repricing is underway. The professional move on these days is often to stand aside until the dust settles — let the event bar print, let VWAP re-anchor to the new reality over the next 30–60 minutes, and then trade the cleaner reclaim or rejection once the line stabilizes. VWAP after a volatility event is most powerful once price has chopped out a new value area around it and the line stops lurching.
The Transition — Reading the Regime Change
The hardest and most profitable read is the transition from one regime to another. A range day that suddenly breaks VWAP decisively and starts sloping is a range-to-trend transition — the reversion fade you'd been running all morning just became a trap. Conversely, a trend day where price finally closes back through VWAP after riding a band for hours is a trend-to-range (or trend-reversal) transition. The signal is always the same shape: price does the thing it hasn't been doing. On a reversion day, that's accepting through VWAP instead of bouncing off it. On a trend day, that's crossing VWAP instead of respecting it. When the market breaks its own pattern at VWAP, believe it and flip your tactics.
VWAP on Multiple Timeframes
VWAP isn't one line — it's a family of lines living on different horizons, and reading them together is where the real edge compounds.
Intraday Layering
On your execution chart (say the 1m or 5m), session VWAP is your primary. But you can also carry a weekly anchored VWAP (anchored to Monday's open) and a monthly anchored VWAP (anchored to the first trading day of the month). These higher-horizon VWAPs tell you where the average participant is over the week and the month, not just the day. When today's session VWAP and the weekly VWAP sit at the same price, that's a heavier level than either alone — a lot of participants across two timeframes are all at breakeven right there.
The Timeframe Hierarchy
When VWAPs on different timeframes disagree, the higher timeframe wins the bias vote. If price is above the daily session VWAP (short-term bulls in control) but below the weekly and monthly VWAPs (medium-term bears in control), the honest read is: today's strength is a countertrend bounce inside a larger down-move. That's a "sell rallies into the higher VWAP" context, not a "buy strength" context. Weighting the timeframes correctly stops you from being right about the day and wrong about the trade.
Nesting the Read
A clean way to run it: use the higher-timeframe VWAP for bias (which direction you're allowed to trade) and the session VWAP for timing (where you enter within that bias). Bias says "we're below the monthly AVWAP, only look for shorts." Timing says "price just rejected the session VWAP from below on a flat-to-down slope — there's the short." The higher line filters, the lower line triggers. That nesting is exactly how desks think about it: strategic level from the big picture, tactical entry from the intraday.
Combining VWAP With Everything Else — Confluence
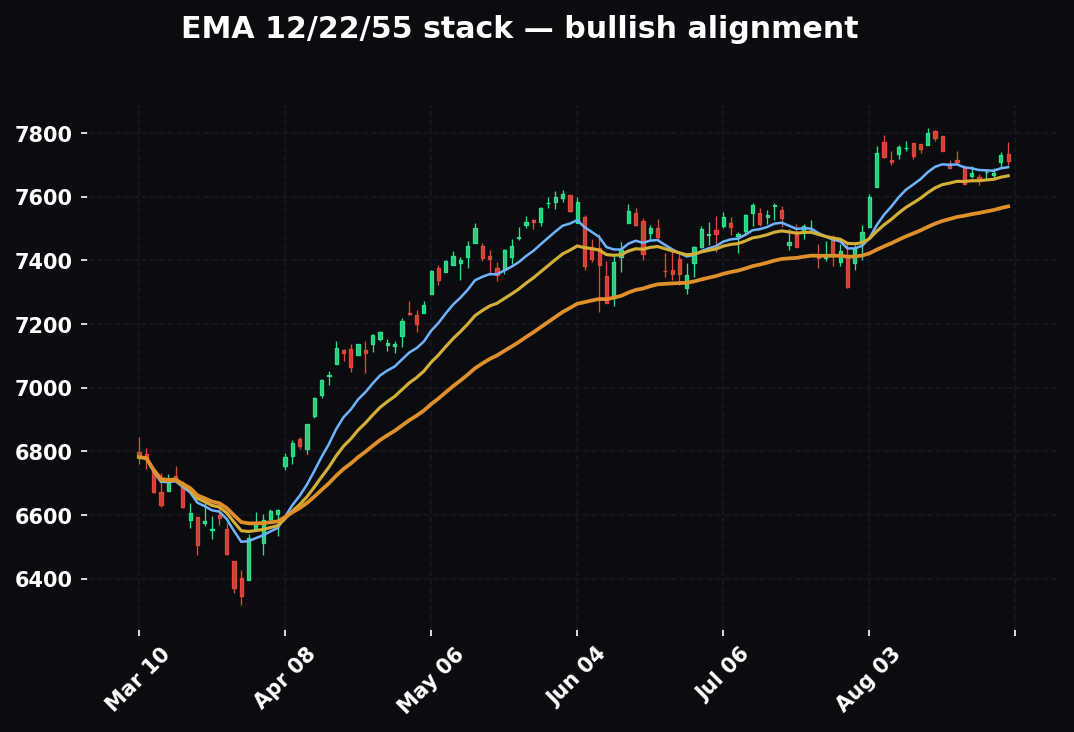
VWAP is strongest when it's not alone. In the HPT framework, trend is defined by the EMA 12/22/55 stack, with the daily 55 as the bias tell. VWAP layers onto that beautifully because it's telling you something the EMAs can't — the volume-weighted average, not just the price average. Two different lenses on the same price, and where they agree, conviction rises.
VWAP + the EMA Stack
When session VWAP and the rising EMA 12/22/55 stack agree — price above both — you have price and volume both confirming the bulls. When they disagree (price above the EMAs but below VWAP), you've got a warning: the trend looks fine but the average participant is underwater today. Trust the confluence, respect the conflict. A pullback that finds support at both the 22-EMA and VWAP at the same price is a far better long than one that only touches one of them.
VWAP + Prior-Day Levels and the Overnight Range
Prior-day high, prior-day low, prior-day close, and the overnight midpoint are already the day's obvious reference points. When VWAP sits on prior-day close or the overnight midpoint, that shared level is heavier than either alone. Price approaching a spot where VWAP, prior-day close, and the overnight mid all converge is approaching a genuine decision point — that's where you want to be paying full attention, not scrolling your phone.
Multi-Anchor Confluence — The Highest-Conviction Read
This is the highest-conviction VWAP read. When your session VWAP, your earnings AVWAP, and your year-open AVWAP all coil into the same price zone, that zone is where an enormous cross-section of participants are at breakeven simultaneously — today's traders, the earnings cohort, and the year's average buyer, all sitting at their own personal line in the sand at once. Price reacts violently at those confluence pockets because so many different decisions get triggered together. Mark them and let them come to you. Don't chase price toward them — let price arrive at the confluence and show you a reaction, then trade the reaction.
VWAP + Volume Profile POC
VWAP is the volume-weighted average; the Point of Control is the single most-traded price. They're cousins, but not the same — VWAP is a mean, POC is a mode. When they overlap, that's the day's true center of gravity — reversion to it is high-probability, and breaks away from it are meaningful. When VWAP and POC are far apart, it tells you the distribution is skewed — lots of volume at one price (POC) but the average pulled elsewhere by a fat tail — and that skew often resolves by price gravitating back toward the POC/VWAP cluster.
VWAP + RSI / MACD Divergence
A 2σ band tag with RSI divergence is a far better fade than either signal alone. The band says "stretched," the divergence says "losing momentum," and the two together are the reversion trade. Picture Worked Example One again, but now add that the RSI made a lower high while price made a higher high into the 2σ band — that divergence is your independent confirmation that the stretch is exhausting. Two unrelated tools pointing at the same conclusion is worth far more than one tool shouting.
The principle: VWAP tells you where the benchmark money is; your other tools tell you whether it's about to act. Timeframe-weighted — a daily anchored VWAP outranks a 5-minute session VWAP when they disagree. Higher timeframe wins the bias vote. Confluence isn't about stacking indicators until one agrees with your bias; it's about independent tools converging on the same price for different reasons.
How the Pros Use It Differently From Beginners
Same line, completely different game. Here's where the gap actually lives.
Beginners treat VWAP as a signal; pros treat it as context. A beginner sees price touch VWAP and thinks "buy" or "sell." A pro sees price touch VWAP and asks "in what regime, from which side, with what slope, into what confluence?" The touch itself is not the trade. The touch plus the context is.
Beginners use one VWAP; pros use a lattice. The beginner has the default session VWAP and nothing else. The pro has session VWAP, a weekly anchor, a monthly anchor, an earnings anchor, and a swing anchor — and trades the spots where several of them agree. The pro's edge often lives entirely in the anchored VWAPs the beginner never draws.
Beginners fade everything; pros know when not to fade. The band-fade is seductive because it works beautifully on balance days — and then a trend day comes and the beginner keeps fading it right into a blown account. The pro's real skill isn't taking the fade; it's recognizing the trend day and refusing the fade.* Knowing when your favorite setup is invalid is worth more than the setup.
Beginners anchor to random candles; pros anchor to events. A pro would never drop an AVWAP on a bar just because it's a local high. They anchor to why the market moved — earnings, the Fed, a gap, a capitulation flush. The anchor has to represent a moment a real cohort of participants entered, or the line has no psychological weight and no edge.
Beginners react to the touch; pros wait for the retest. The reclaim, the rejection, the break — a beginner trades the first poke through the line. A pro waits for price to come back and prove the level by holding it (or failing it) on the retest. That patience turns a coin-flip into an edge, and it's the difference between Worked Example Two (bought the retest, made 3:1) and the trap of buying the first poke.
Beginners think VWAP predicts; pros know it describes. The pro never forgets VWAP is a cumulative average of what already happened. It describes where flow has been leaning with high fidelity, which creates a real edge — but it's an edge with a risk stop on every trade, not a prophecy. That humility is why the pro survives the day the edge doesn't work.
Beginners watch VWAP; pros watch behavior at VWAP.* The line matters far less than what price and volume do when they reach it. A pro is reading the candle, the volume, the speed of the approach, whether the touch is the first or the third of the day. The line is just the spot where the information gets revealed; the read is in the reaction.
The Common Mistakes
1. Trading VWAP as a magic line. VWAP is not a buy-here-sell-there level. It's a reference. Blindly buying every tag of VWAP will get you run over on trend days when price slices through it and never looks back. Always ask "reversion or acceptance?" first. The line is a question, not an answer.
2. Ignoring the regime. The single biggest error. Fading the 2σ band on a strong trend day is how accounts die — you're standing in front of the exact one-directional flow the band is measuring. Flat VWAP → fade. Sloped VWAP → follow. Read the slope before you read anything else, every single time.
3. Fading VWAP early in the session. In the first 15–30 minutes VWAP is light and jumpy — a handful of big bars whip it around, as the math showed you. Signals off VWAP before it "sets" are noise dressed up as edges. Let volume accumulate and the line stabilize before you trust a rejection. The 9:05 touch and the 12:30 touch are not the same evidence.
4. Wrong anchor on the AVWAP. Anchoring to a random candle instead of a meaningful event gives you a line with no participants behind it — no psychology, no edge. The anchor must be a moment the market cared about: earnings, a capitulation low, an IPO, a Fed day. No event, no anchor.
5. Using VWAP on the wrong timeframe or instrument. VWAP needs real volume to mean anything. On thin, illiquid names or on continuous-contract data where volume is patchy, it degrades badly. And session VWAP on a weekly chart is meaningless — the reset happens every day, so on a weekly candle it's noise. Match the anchor to the horizon you're trading.
6. Forgetting VWAP is backward-looking. It's a cumulative average of what already traded. It describes where flow has been leaning, not a guaranteed future. It's an edge, not a crystal ball. Manage the risk on every trade regardless of how clean the setup looks.
7. Only using session VWAP. Day traders who never drop an anchored VWAP are leaving the best levels on the table. The earnings anchor and the swing-low anchor are often cleaner than anything on the intraday chart. Ignoring AVWAP is ignoring half the tool.
8. Buying the poke instead of the retest. Trading the first bar through a VWAP level, before price comes back and proves the level holds, is trading a rumor. The retest-and-hold is the confirmation. Waiting for it costs you a few points of entry and saves you from every failed breakout.
9. Confusing globex and cash-session VWAP. On futures especially, the 24-hour VWAP and the regular-hours VWAP can sit points apart and tell different stories. Trading off the wrong one means your line doesn't match the level price actually respects, and you'll think VWAP is "broken" when really you're looking at the wrong session anchor.
10. Over-cluttering the chart with anchors. Ten anchored VWAPs means some line is always near price, which feels like confluence but is actually noise — you've manufactured a level for every price. Keep three or four anchors that each have a real story. Confluence means independent lines agreeing, not a forest of lines guaranteeing a coincidence.
11. Fading into 3σ on a high-volatility repricing. The 3σ band on a Fed day or a shock is not a stretched rubber band — it can be the leading edge of a genuine repricing that keeps going. Treating an outlier band tag during a volatility event as an automatic fade is stepping in front of a freight train. Wait for the line to re-anchor.
12. Letting VWAP override price action. VWAP is context, not a command. If price is screaming a message — a decisive break, a clear reversal pattern, a volume climax — and VWAP disagrees, the raw price action often wins. VWAP earns its place in the read; it doesn't get to overrule what's plainly happening on the tape.
The Playbook — How to Actually Use It Monday
Here's the workflow to run live, start to finish.
Pre-market. Put session VWAP on your intraday chart, anchored to the session you actually trade (cash open for index intraday). Drop three anchored VWAPs: last earnings, the most recent significant swing low (or high, whichever is in play), and the year open. Note where each sits and where any two of them converge — those convergence zones are your key levels for the day. Write the two or three numbers down. If you can state them out loud before the bell, you're ahead of most of the screen.
At the open. Don't trade the first 15 minutes off VWAP — let it set. Watch which side of VWAP price organizes on. Note the VWAP slope as it forms. Is price crossing VWAP easily (range forming) or holding one side and riding a band (trend forming)? You're diagnosing the regime before you take a single trade.
Building the bias. Above a rising VWAP that agrees with the daily EMA 12/22/55 stack → long bias, buy pullbacks to VWAP or the 1σ band. Below a falling VWAP → short bias, sell rallies into it. Flat VWAP → reversion mode, fade the 2σ bands back to the mean. Check the higher-timeframe VWAPs: if the weekly/monthly anchor disagrees with the day, downgrade countertrend trades to scalps and respect the bigger line.
Taking the trade. Enter at a confluence — VWAP or a band tag lining up with an anchored VWAP, a prior-day level, or a POC. A reversal candle or a hold-on-retest is your trigger; the first poke is not. Stop goes beyond the level that invalidates the read — past the band and spike high on a fade, below the reclaimed line on a reclaim. Size so you're risking a fixed, small fraction of the account on every trade, no exceptions, no "this one's special."
Managing it. First target is the obvious magnet — VWAP itself on a band fade, the next anchored VWAP on a trend trade. Bank partials there. Only hold a runner when the regime supports it and the math still clears 1:3 R/R to the next real level. If price breaks and accepts through your target level, the regime may be flipping — respect it, don't fight the new flow. Trail under higher lows on a trend runner; get flat on a reversion runner once price reaches the opposite band.
The one rule underneath all of it. The levels do the work; discipline banks it. VWAP hands you the map — where the size is leaning, how stretched price is, which side is green. It won't hand you patience or position sizing. That's on you, every day, and it's the part no indicator will ever do for you.
Frequently Asked Questions
Does VWAP work on stocks, futures, forex, and crypto equally? It works best where volume data is real and centralized. Stocks and futures are ideal — one exchange, clean volume. Crypto works on a per-exchange basis but fragments across venues. Spot forex is the weak case: there's no centralized volume, so "VWAP" there is built on tick-volume proxies and is far less reliable. The rule: the more real, centralized volume behind it, the more the line means.
What's the best VWAP setting? For intraday index and futures trading, session VWAP anchored to the cash open, with 1σ and 2σ bands, off typical price. That's the workhorse. Everything else — anchored VWAPs, extra bands — is added deliberately for a reason, not by default.
Session or anchored — which should I prioritize? Session VWAP for the day's fight, anchored VWAP for the bigger context. If forced to pick one for pure day trading, session VWAP; but the best reads always use both, with the anchored lines defining bias and the session line defining timing.
Can I use VWAP as a standalone strategy? Not well. VWAP is a context and confluence tool. Mechanically buying every VWAP touch loses money on trend days; mechanically fading every band tag loses money in trends too. It shines as one leg of a read — regime + VWAP + confluence + trigger — not as a lone signal.
Why does price sometimes ignore VWAP completely? Trend days and high-volatility repricings. When institutional flow is one-directional, price accepts being far from VWAP and the mean-reversion magnet simply doesn't engage. "Ignoring" VWAP is the signal — it's telling you you're in an acceptance regime, not that the tool is broken.
How do I know if it's a trend day or a range day early enough to matter? Watch the first hour's behavior at VWAP. Repeated easy crosses and a flat line → range. Price holding one side, riding a band, VWAP sloping → trend. The opening range break relative to VWAP is another tell: a decisive break of the opening range away from VWAP that holds usually kicks off a trend day.
Does VWAP repaint or change after the fact? No. VWAP for a given bar is fixed once that bar closes — it's a cumulative calculation of completed data. The current forming value updates as the live bar trades, like any indicator, but historical VWAP values don't repaint. What you saw is what happened.
Should the bands be standard deviation or something else? Standard-deviation bands are the standard and the most informative because they adapt to the day's volatility. Some traders use fixed-percentage or ATR-based envelopes; those are fine but less common. Whatever you choose, keep it consistent so your "2σ stretched" read means the same thing every day.
Quick-Reference Cheat-Sheet
What it is: Volume-weighted average price — the average fill of the day, weighted by where volume traded. VWAP = Σ(typical price × volume) ÷ Σ(volume), cumulative from an anchor. Participation wins, not recency.
Why it works: Institutional execution algos are benchmarked to beat VWAP → mechanical buying below it, selling above it → it acts as a magnet on balanced days. A magnet made of other people's incentives.
Session VWAP: Resets daily. Your intraday bias line. Above = bulls control the day, below = bears. Match the session anchor (cash vs globex) to what you trade.
Anchored VWAP: You pick the start. Anchor to events — earnings, swing high/low, IPO, year/quarter open, Fed day. It's the average price of everyone in the move since that event, and the line between that cohort being green or red. Keep it to 3–4 meaningful anchors.
Bands (std-dev): 1σ = normal range, 2σ = stretched (fade on reversion days, ride on trend days), 3σ = outlier/spike (respect, don't blind-fade).
Regime read (do this first):
- Flat VWAP → REVERSION → fade the bands back to VWAP.
- Sloped VWAP → ACCEPTANCE / TREND → buy pullbacks to VWAP/1σ (up) or sell rallies (down).
- Bands blowing wide on a shock → HIGH-VOL → stand aside, let it re-anchor.
Reversion vs acceptance: Clean bounce off VWAP = reversion (trade toward mean). Break-and-hold through VWAP on the retest = acceptance (regime flipped, follow it). Believe the retest, not the first poke.
Multi-timeframe: Higher-timeframe VWAP = bias filter; session VWAP = entry timing. When they disagree, the higher timeframe wins the bias vote.
Confluence stack: VWAP + EMA 12/22/55 + prior-day levels + POC + multi-anchor overlap + RSI/MACD divergence. Best trade = session VWAP, an anchored VWAP, and another level all at one price for independent reasons.
The five-step read: (1) Which side? (2) What slope? (3) Reversion or acceptance? (4) Where are the bands? (5) What anchors are near?
Top mistakes: Trading it as a magic line · ignoring the slope/regime · fading it in the first 15 min · anchoring to a meaningless candle · using it on thin volume · forgetting it's backward-looking · never using anchored VWAP · buying the poke not the retest · confusing globex/cash sessions · over-cluttering with anchors · fading 3σ into a repricing · letting VWAP override loud price action.
Trade management: Enter at confluence on a trigger, stop past the invalidation level, first target the magnet, bank partials, only hold a runner when the regime supports it and the math clears 1:3.
Learn this line and you're reading the same page as the desks. That's rare. Don't waste it by trading it lazily — read the regime, wait for the retest, stack the confluence, and let discipline bank what the levels hand you.

Bound by rules, feared by trade.